Economy

Marking the debut of Chief Technology and Innovation Strategist Matt Dyson, this month’s Global Market Outlook examines Matt’s views on the presence and durability of moats for companies at various segments of the AI chain.
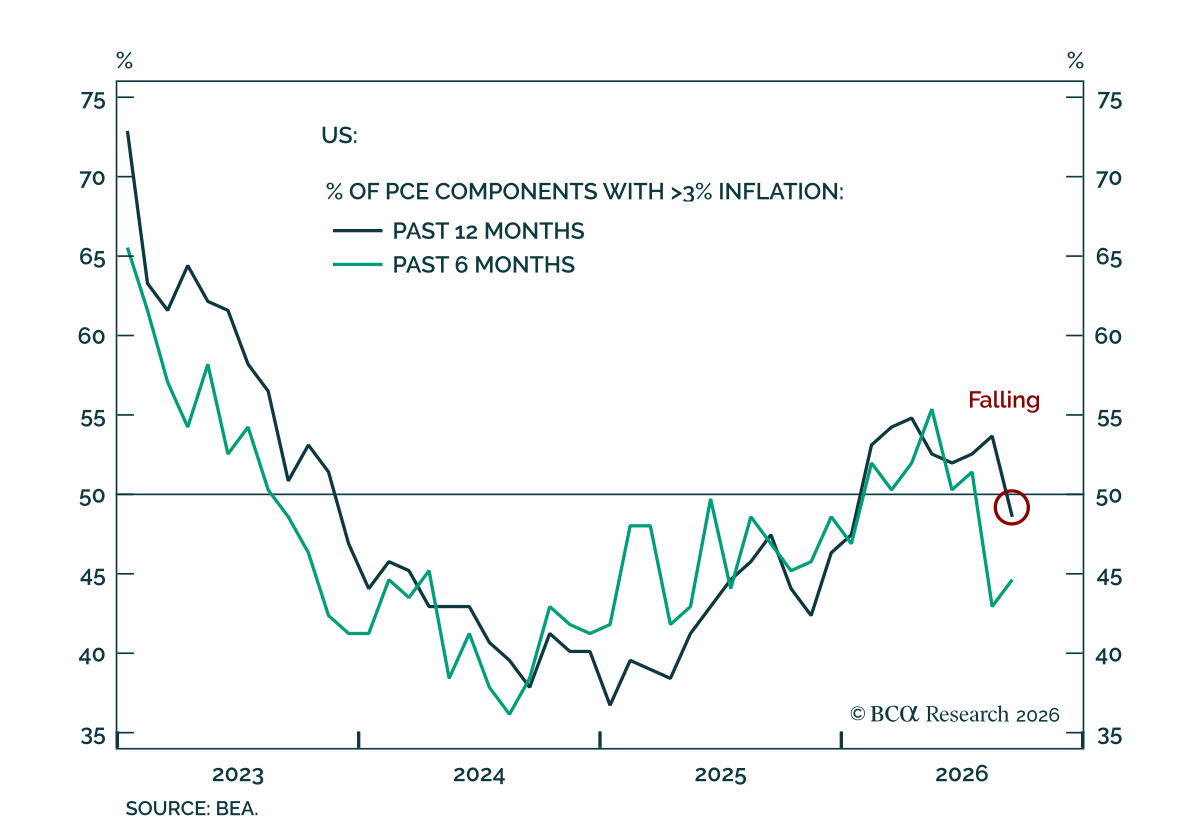
Neither the Q3 GDP release nor the September inflation data will likely shift the Fed away from a quarterly pace of rate hikes. The advance Q3 estimate for US GDP was released on Thursday, alongside the September personal income and outlays report. Annualized…

The ECB is unlikely to take interest rates above neutral unless energy prices move meaningfully higher from here. The European Central Bank kept its policy rates unchanged on Thursday, in line with expectations. Compared with June and September, the statement…

The Fed will hike rates at a pace of 25 bps per quarter until either falling inflation or tighter financial conditions cause it to stop.

October S&P Global Flash PMIs signal that the US economy continues to show solid momentum, while the euro area growth outlook is softening. The US composite index eased to 57.6 from 58.4, in line with estimates. The manufacturing component surprised on the…
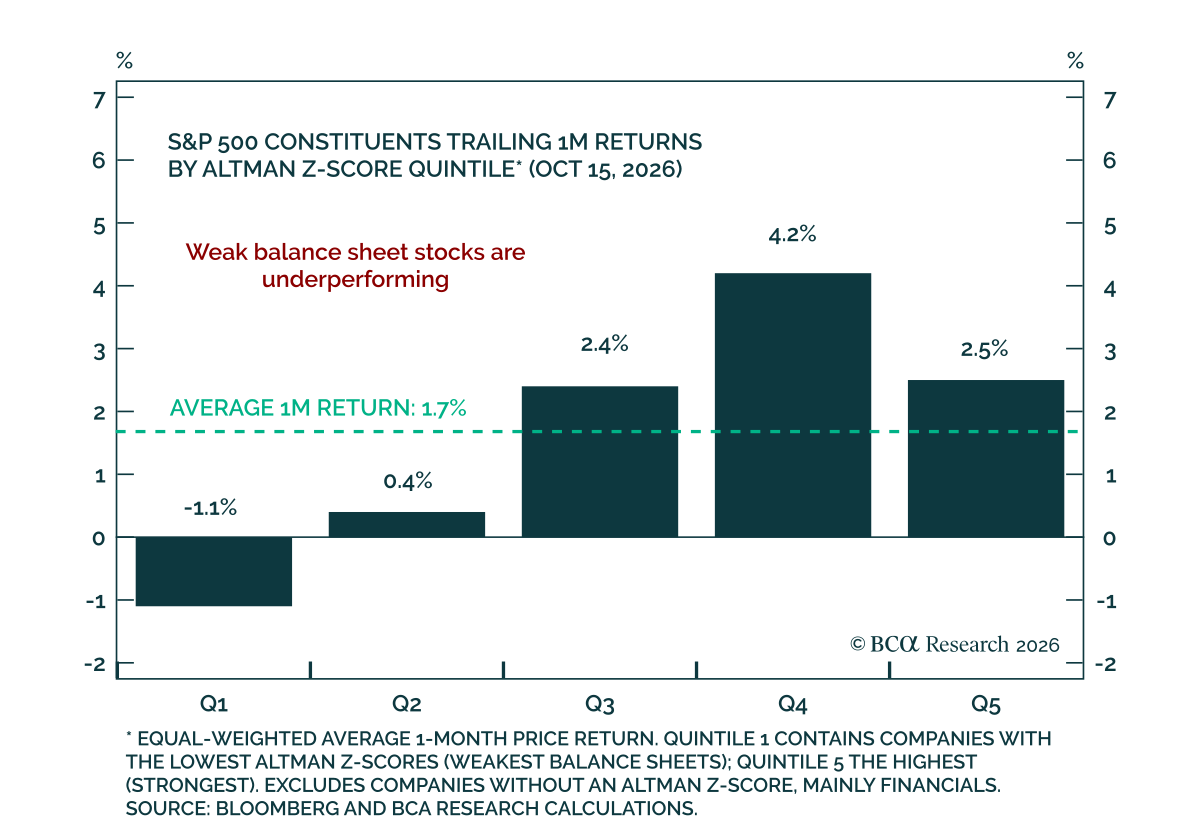
Our US Equity strategists recommend fading wider credit spreads. Investors should lean into quality ahead of Q3 earnings, rather than de-risking. Credit spreads have widened as Treasuries have sold off, punishing stocks with weak balance sheets. But the…

Credit spreads have widened as bond risks intensified, pressuring weak-balance-sheet companies. But the stress is narrow and valuations have already compressed, so equity risks look manageable. Rather than de-risk, we would lean into quality: large over small caps, quality capex, and defensible Tech margins, and look to Q3 earnings for confirmation.

The New York regional Fed services index fell in October, but hiring stayed steady. The overall business activity index declined from -9 in September to -21 in October based on current conditions, and expectations six months ahead declined from 5 to -5. The…

“Core” US retail sales growth was tepid in September, but meaningfully stronger than confidence measures implied. Headline sales rose 0.8% m/m, a slowdown from August but above consensus expectations. The core measure excluding autos and gas also increased…
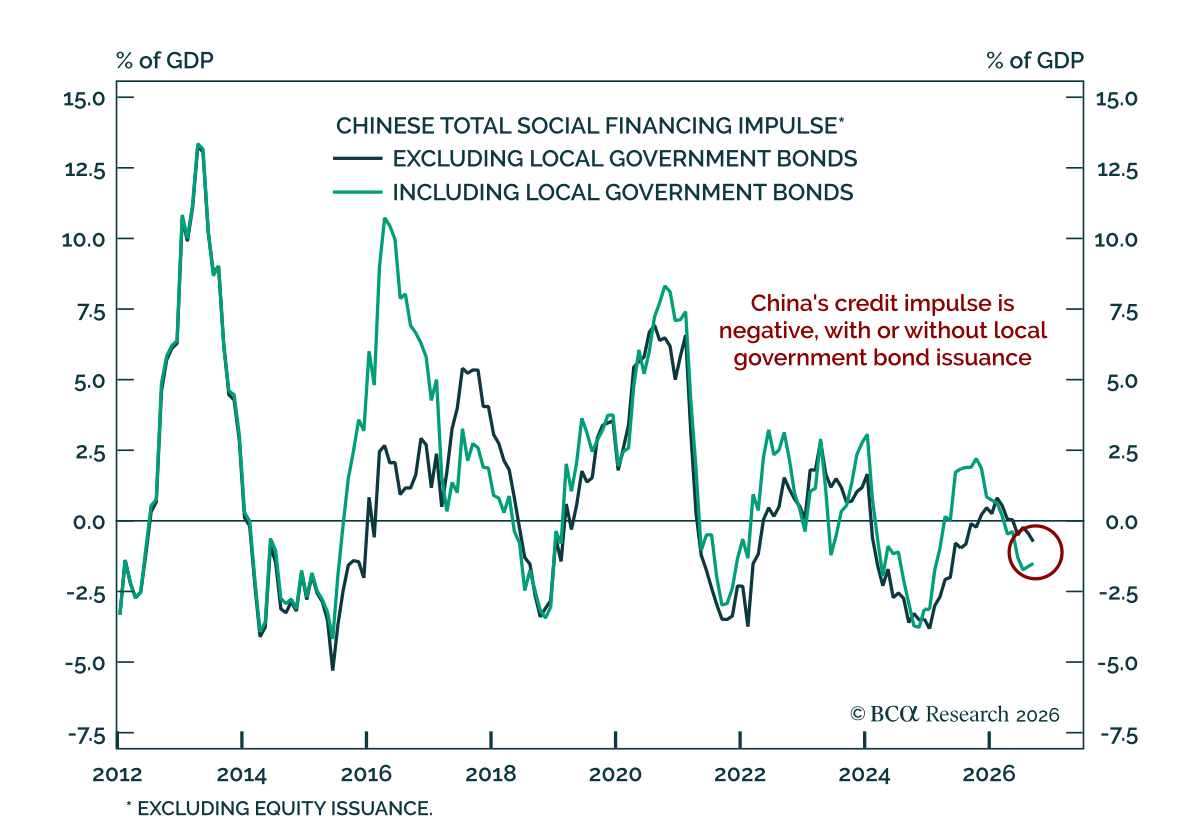
China’s September inflation, trade, and credit data do not point to an improving domestic economy. Producer price inflation accelerated in September, but energy drove most of the increase. Consumer price inflation was unchanged, suggesting that producers…