Inflation

Japan’s rising wage growth in September reinforces the Bank of Japan’s rate tightening campaign and supports our underweight in JGBs. Headline nominal wage growth accelerated to 4.6% from 3.9% in August and came in well above the market consensus of 3.8%. It…

Euro area wage and inflation data reinforce the view that today’s labor dynamics differ from the 2022 energy shock, favoring Bunds over Treasuries. The ECB wage tracker points to continued deceleration in wage growth pressures in 2027, with wage growth…

The October jump in Swiss headline inflation does little to support bets on sustained SNB rate increases and leaves the franc as the most attractive funding currency for carry trades. Inflation accelerated to 1.5% year on year in October, the highest since…
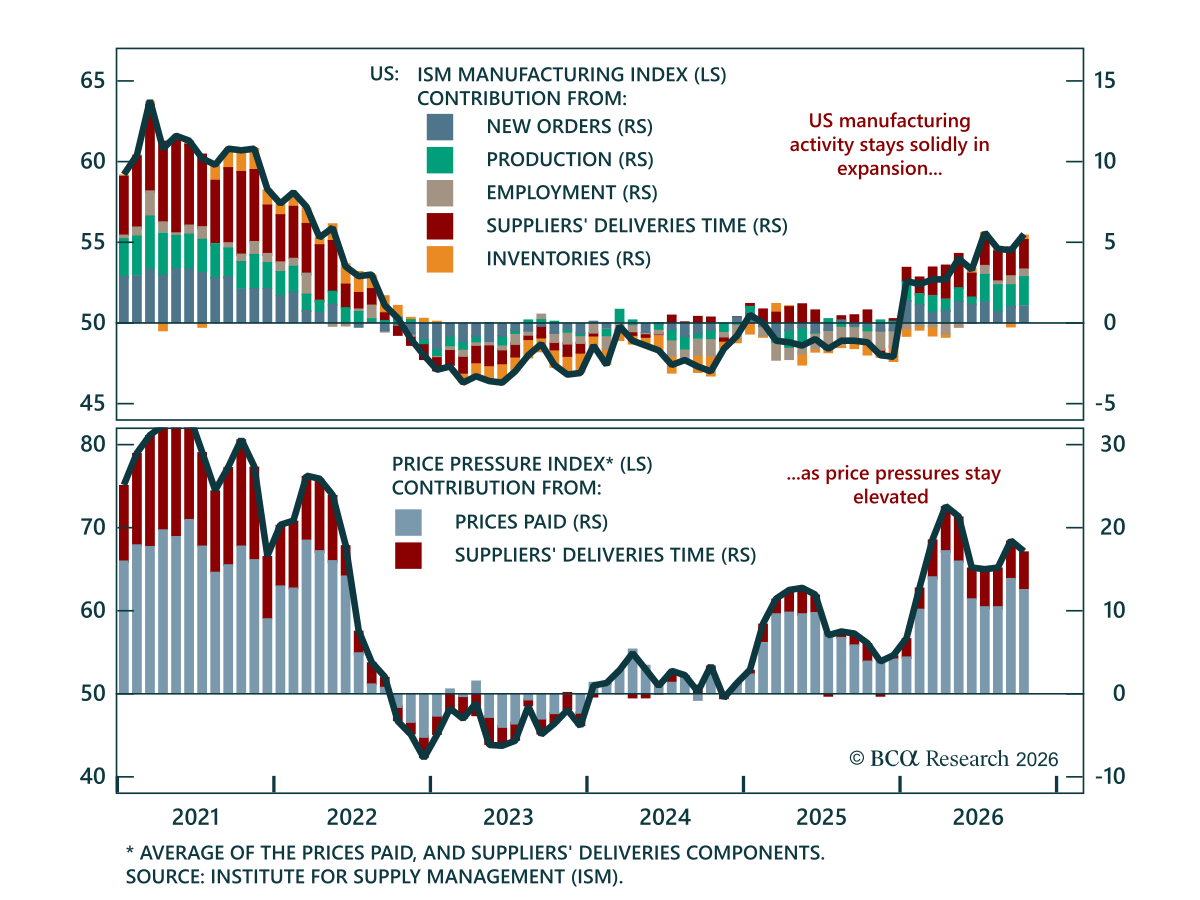
October’s ISM Manufacturing PMI reinforces the resilient US economic backdrop, which favors an overweight stance toward equities relative to bonds. The index rose to 55.5, remaining solidly in the expansion zone and exceeding market consensus by one point.…
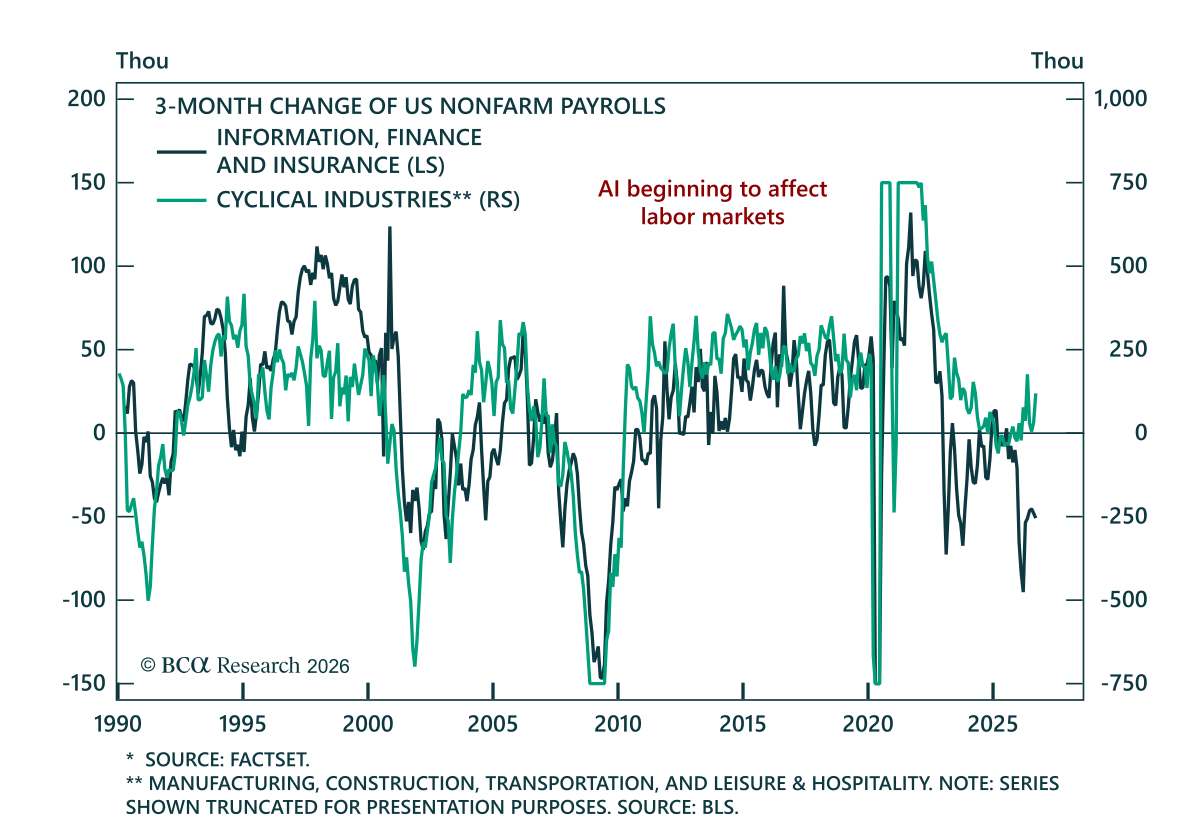
Our Portfolio Construction strategists remain bullish on risk assets but express that view through barbells across the portfolio. October looked cataclysmic from the headlines, with neocloud debt spreads spiking and Alphabet suffering its worst one-day loss…

US Treasury yields have fallen below our fair value estimate as investors rotated out of AI equities and into fixed income. We lay out why near-term inflation risks argue for a rebound, and the tactical trades we initiate to position for it.

Despite October’s AI selloff, indices remain resilient thanks to historically high dispersion. We remain bullish, but with barbells across the portfolio. Hedge equity with equity: Overweight Technology and Healthcare. Remain overweight high yield. Downgrade linkers and upgrade nominal bonds. Upgrade tail risk protection to overweight as a hedge against a resumption of the war.
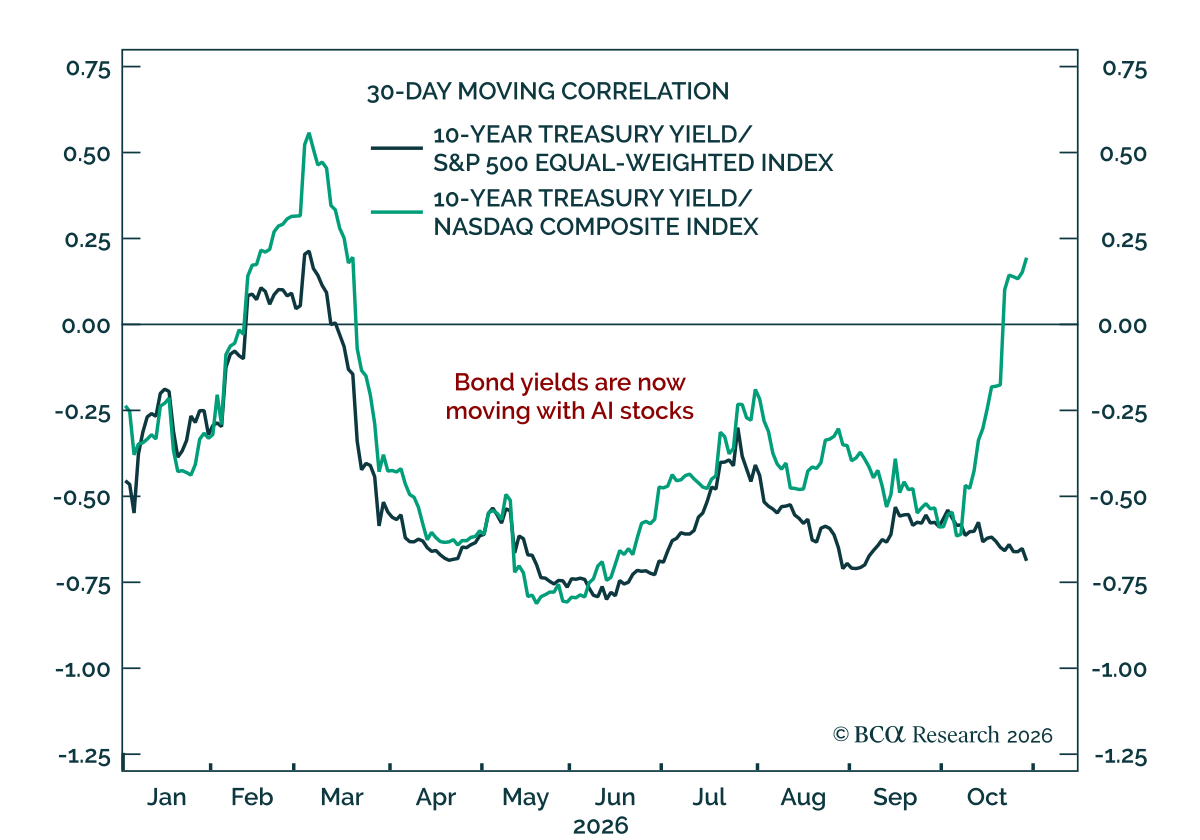
AI equity performance has replaced oil as the main driver of US Treasury yields, setting up a rotation out of AI stocks into the rest of the market. Our Chart Of The Week comes from Ryan Swift, our Chief US Bonds Strategist. Bond yields now track AI stocks…

Stronger Q3 euro area growth was likely AI-driven and obscures underlying weakness. Real Q3 euro area GDP came in stronger than consensus expectations. Real GDP grew 1.7% q/q annualized, which was slower than Q2 but meaningfully higher than expectations.…
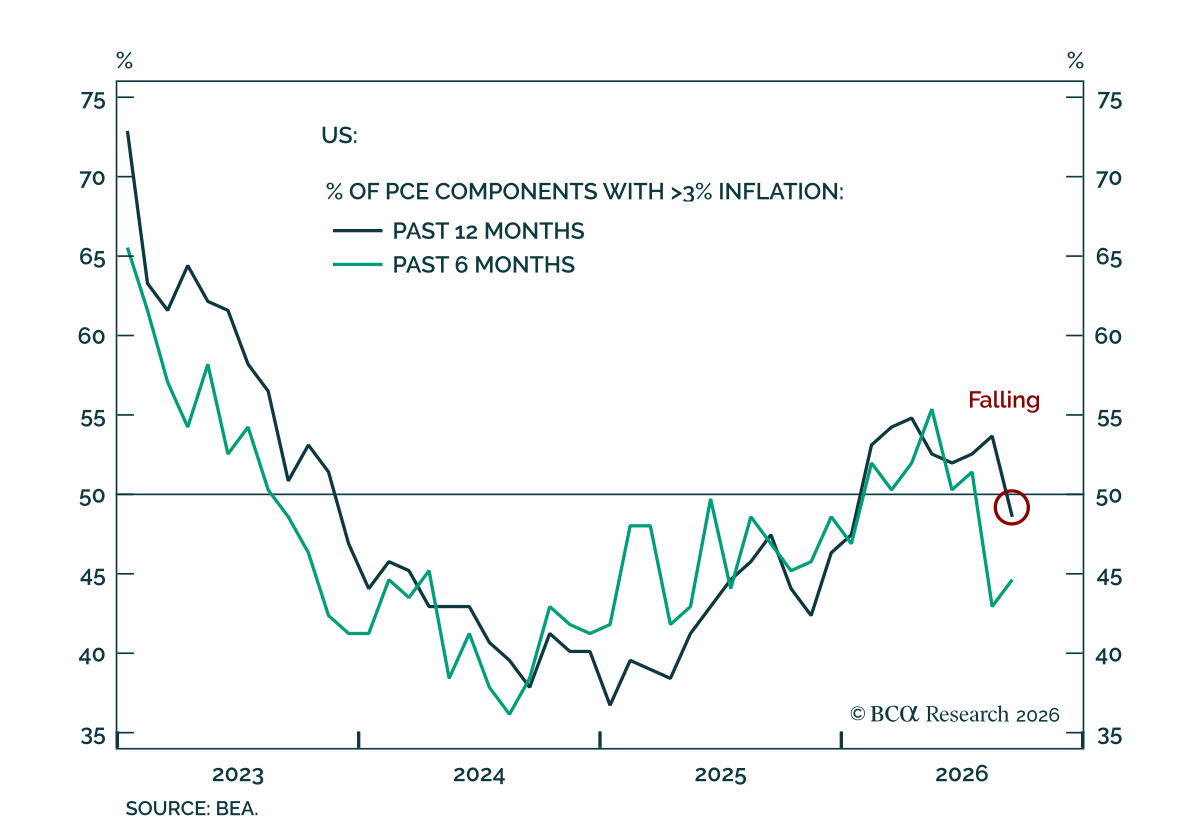
Neither the Q3 GDP release nor the September inflation data will likely shift the Fed away from a quarterly pace of rate hikes. The advance Q3 estimate for US GDP was released on Thursday, alongside the September personal income and outlays report. Annualized…