Energy
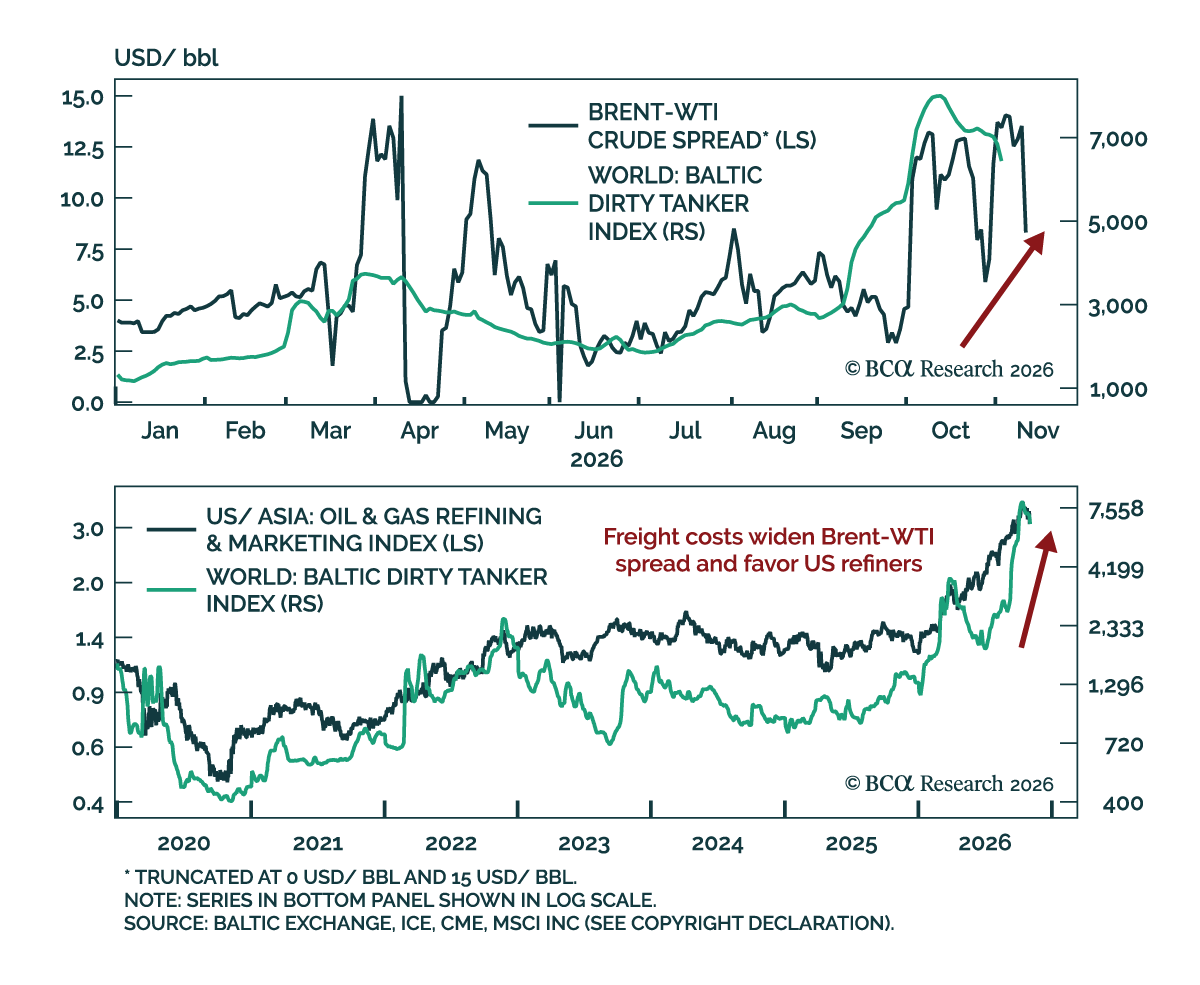

Commodities have diverged sharply in recent months. We explain why energy prices are likely to stay elevated after the US midterms, why gold’s slide should prove limited, and how we are positioning for the months ahead.
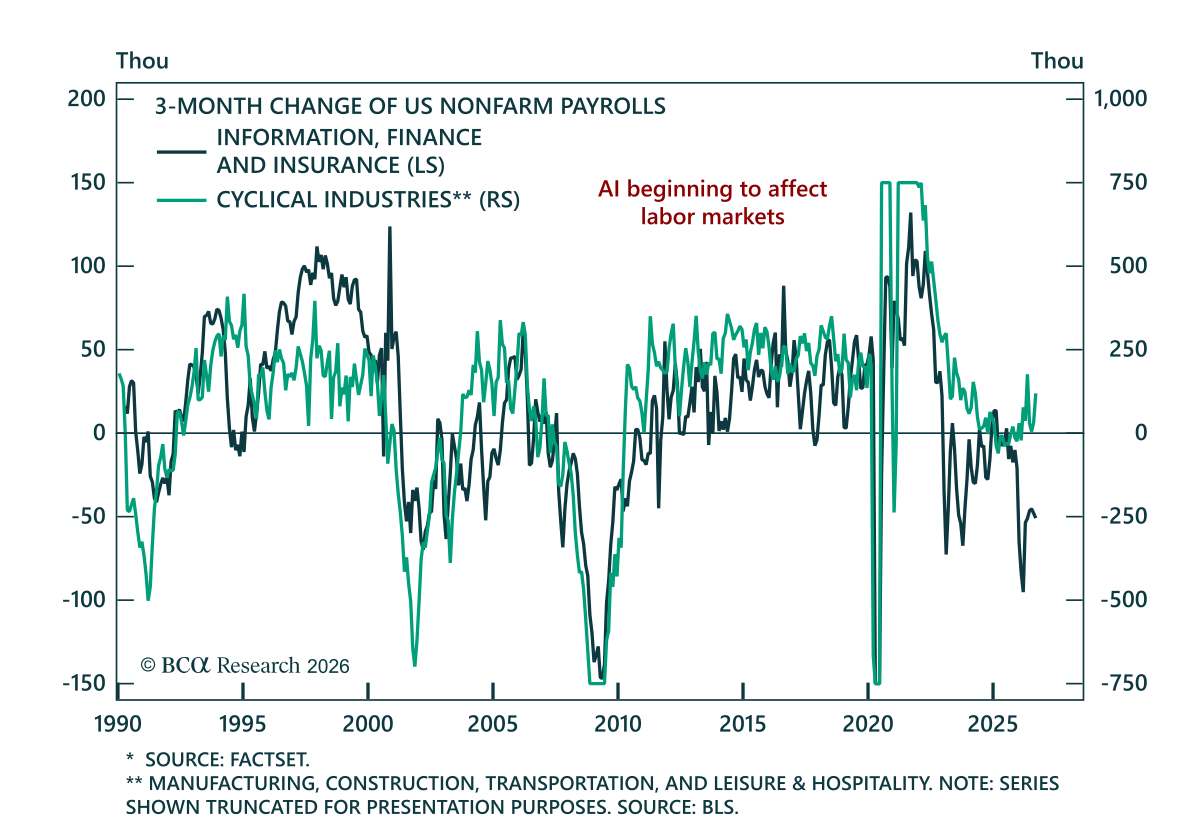

Despite October’s AI selloff, indices remain resilient thanks to historically high dispersion. We remain bullish, but with barbells across the portfolio. Hedge equity with equity: Overweight Technology and Healthcare. Remain overweight high yield. Downgrade linkers and upgrade nominal bonds. Upgrade tail risk protection to overweight as a hedge against a resumption of the war.

An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury announcement of upsized buyback operations, bond yields are likely to remain elevated over the coming months. Rising crack spreads have reduced the demand for crude, which is not encouraging for global growth. On the FX front, recent intervention to support the yen will probably be insufficient, but there is significant long-term upside for the currency.

As long as the AI boom keeps booming, all other investment considerations will remain on the back burner. However, if the AI trade fizzles, this would expose deep-seated problems within the global economy, which could very well lead to an economic downturn as early as next year.

The UK economy is becoming increasingly fragile, but the investment outlook is improving. Slower growth and a more dovish BoE will support gilts, while UK equities will likely benefit from a favorable sector mix and a weaker pound.


Ebola remains one of the world's deadliest viral diseases, but it is far less transmissible than COVID-19 or influenza. The most likely outcome remains containment rather than a global pandemic.

South Africa’s ambitious reform agenda will take time to bear fruit. Meanwhile, the country faces a stagflationary squeeze as inflation rises while growth slows. South African stocks, bonds, and currency are all vulnerable.