Skip to main content

Switzerland

The October jump in Swiss headline inflation does little to support bets on sustained SNB rate increases and leaves the franc as the most attractive funding currency for carry trades. Inflation accelerated to 1.5% year on year in October, the highest since…
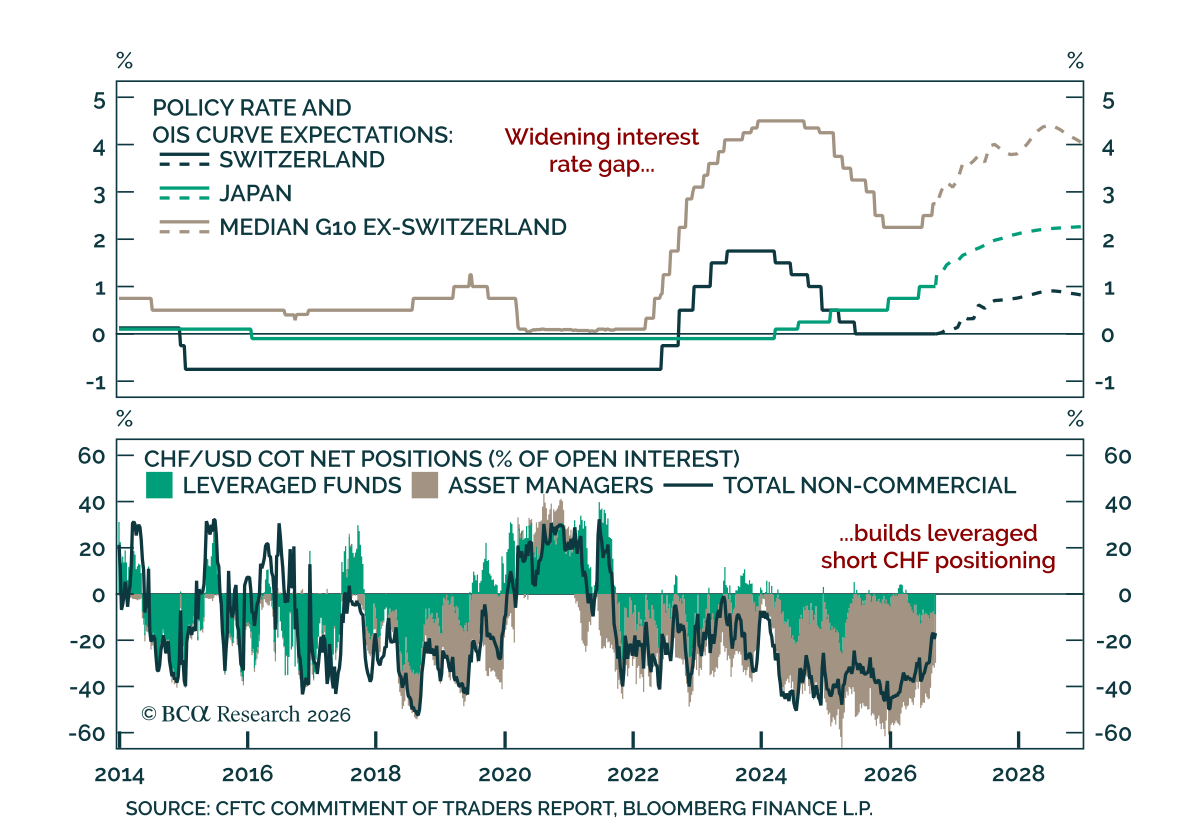
The Swiss National Bank's decision to hold its policy rate at 0% at the September meeting confirms the franc as the market's cheapest and most attractive carry-funding currency. A recent string of positive data surprises, driven partly by a temporary exports…

The Section 122 tariffs under the US Trade Act of 1974 are more favorable to Europe; the trade-weighted tariff rate falls to 10.45%, from 11.74% pre-ruling. This positive development does not change our overall views on Europe, as we expected lower tariffs ahead of the US midterms. 

Switzerland is modestly better positioned following the SCOTUS tariff ruling. The path to a US trade agreement was bumpy, with Switzerland initially facing tariffs of 39% before securing a preferential rate of 15% last December. Following the SCOTUS ruling…

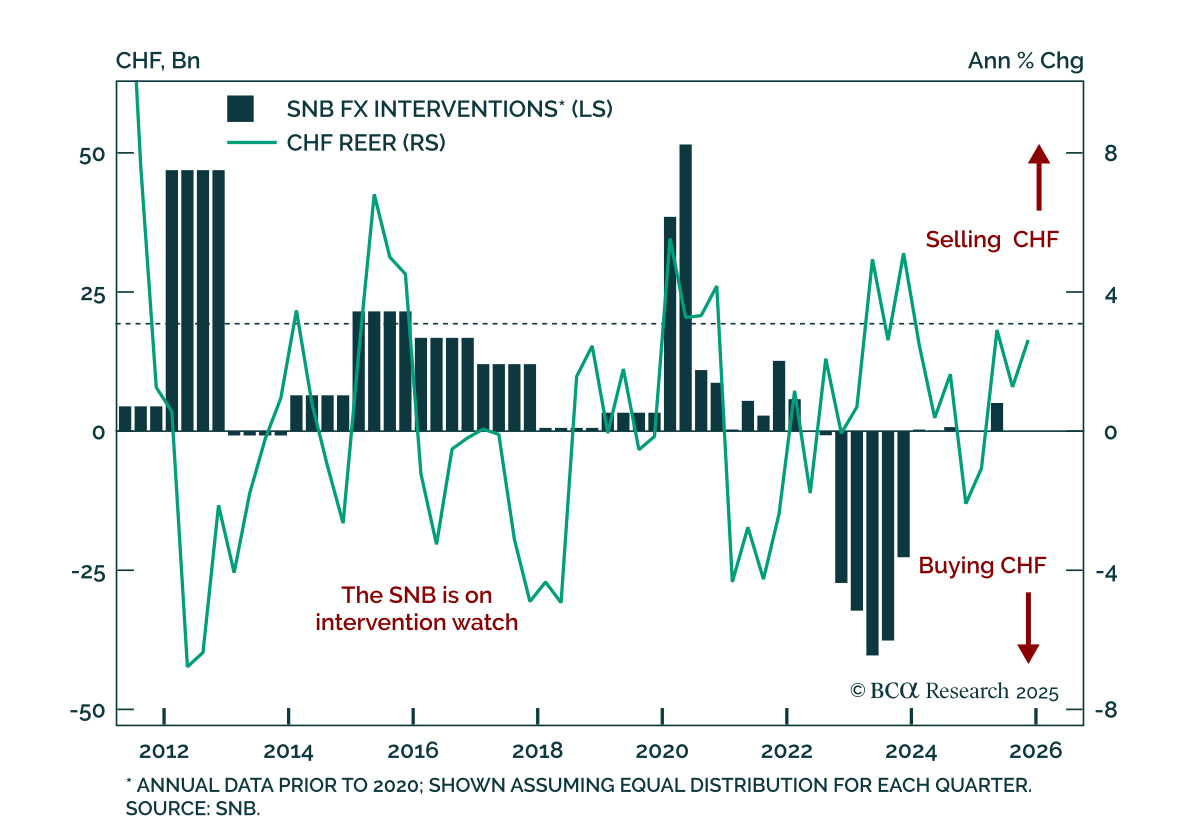
We spent last week meeting investors in Switzerland. This Strategy Insight revisits the most prominent topics we discussed, including repatriation fears, SNB intervention, and Dutch pension reform.

Swiss inflation remains near the lower bound of the SNB’s target, with a strong CHF weighing on activity and inflation. January CPI fell 0.1% m/m and rose 0.1% y/y, while core increased 0.5% y/y. These readings place inflation toward the lower end of the…
Use CHF as a funding currency and stay long EUR/CHF and JPY/CHF as deflationary pressures lower the SNB’s threshold for easing. The SNB left the policy rate unchanged at 0%, reiterating that current settings remain appropriate and that the bar for returning…
Swiss October inflation cooled further, but not enough to trigger an SNB rate cut. Headline CPI rose 0.1% y/y, slowing from 0.2% in September, while core inflation missed estimates at 0.5%, down from 0.7%. Inflation now sits at the bottom of the SNB’s 0–2%…

Markets are increasingly pricing an end to the global easing cycle, with many central banks expected to remain on hold. But uncertainty remains high, and policy surprises are likely going into 2026. This Strategy Report breaks down the current drivers behind G10 central bank policies, and how to position for the next moves across FX and fixed income.

Markets are increasingly pricing an end to the global easing cycle, with many central banks expected to remain on hold. But uncertainty remains high, and policy surprises are likely going into 2026. This Strategy Report breaks down the current drivers behind G10 central bank policies, and how to position for the next moves across FX and fixed income.