Elections

US institutions are prevailing over an unorthodox personality, implying policy adjustment and a decent backdrop for equity markets. But the Iran war is an immediate and acute risk to the global macro and market outlook.

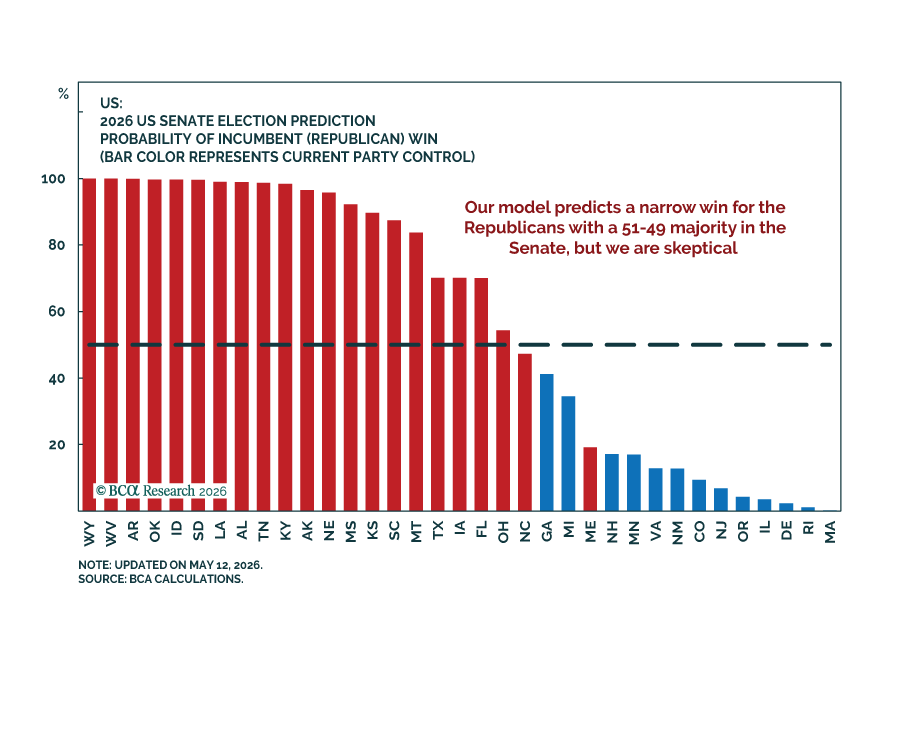
Democrats look to be clinching a Senate victory in the final day of the campaign, but Iran, not the Senate, poses the real risk.

Brazil’s elections have turned into a game of roulette for investors. Bulls and bears were each wrong-footed between the first and second rounds of elections. We are downgrading Brazilian equities, local bonds, and sovereign credit to underweight within their respective EM portfolios.
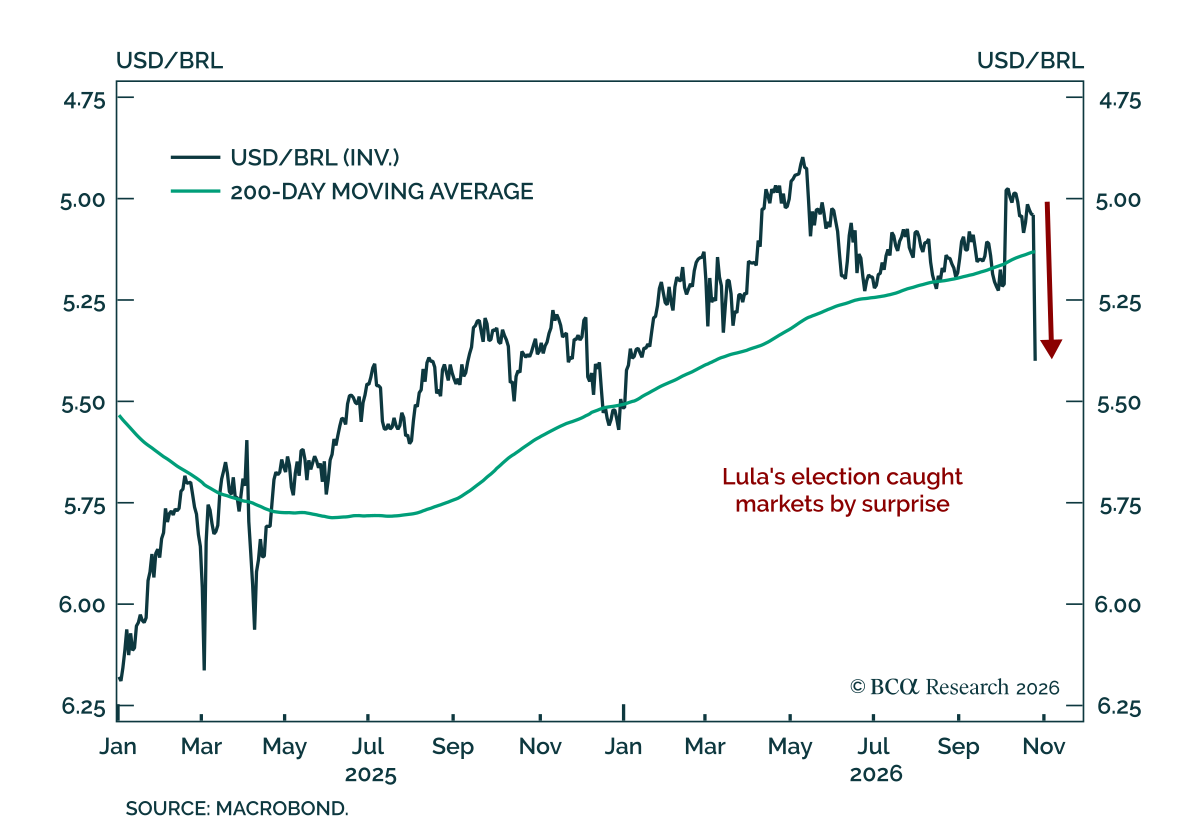
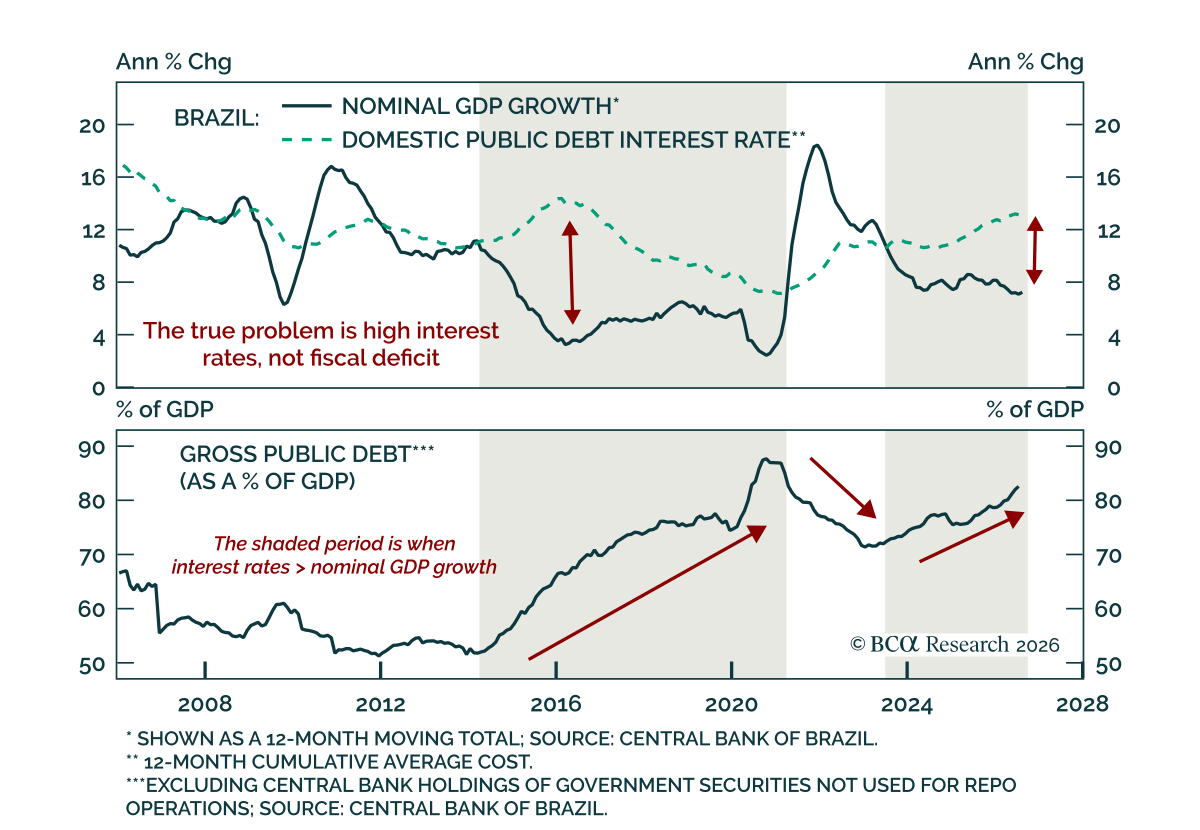

The most bullish development for Brazil from the weekend’s elections was not the higher odds of a right-wing presidency, but the likely president’s (Flávio Bolsonaro) stronghold in Congress. Upgrade Brazilian fixed-income markets to overweight and equities to neutral within their respective EM portfolios.

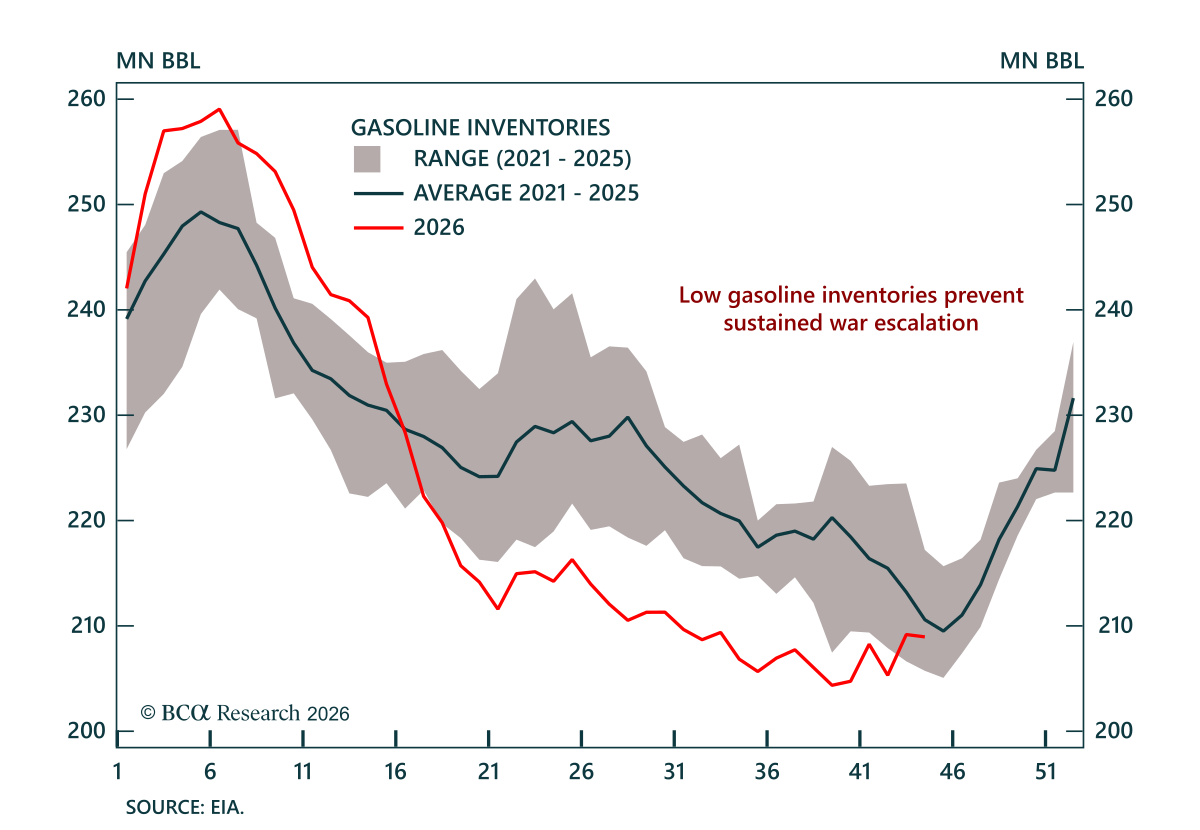
An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury announcement of upsized buyback operations, bond yields are likely to remain elevated over the coming months. Rising crack spreads have reduced the demand for crude, which is not encouraging for global growth. On the FX front, recent intervention to support the yen will probably be insufficient, but there is significant long-term upside for the currency.

The US-Iran deal offers temporary relief from oil supply risk, but both Hormuz and trade tensions could revive in 2027.