AI and Markets
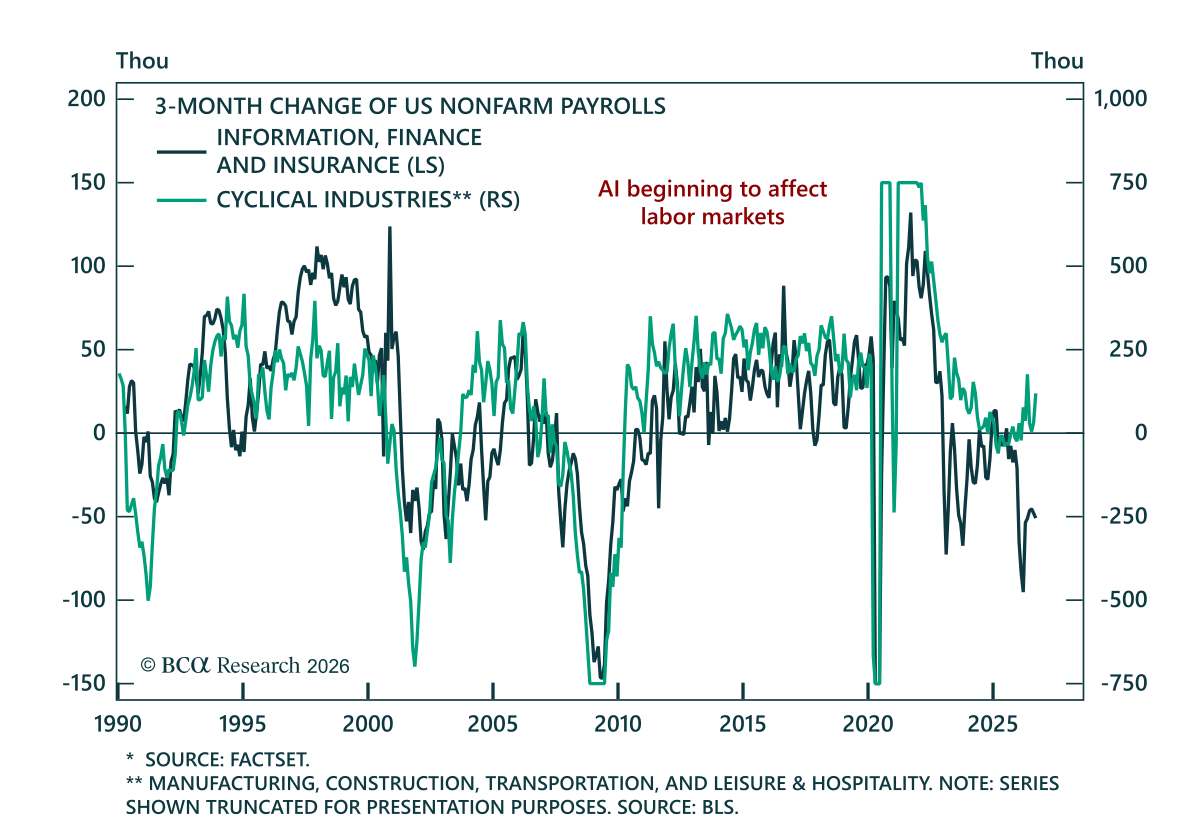

Despite October’s AI selloff, indices remain resilient thanks to historically high dispersion. We remain bullish, but with barbells across the portfolio. Hedge equity with equity: Overweight Technology and Healthcare. Remain overweight high yield. Downgrade linkers and upgrade nominal bonds. Upgrade tail risk protection to overweight as a hedge against a resumption of the war.
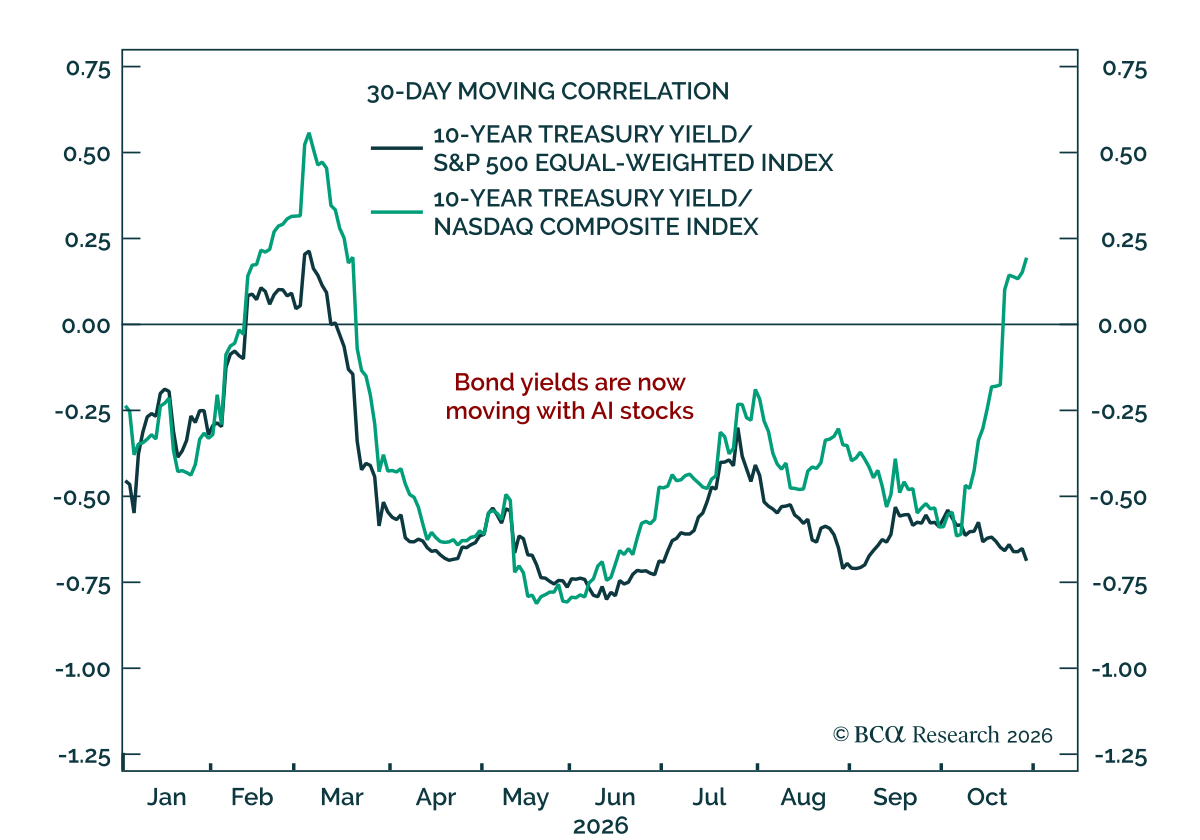

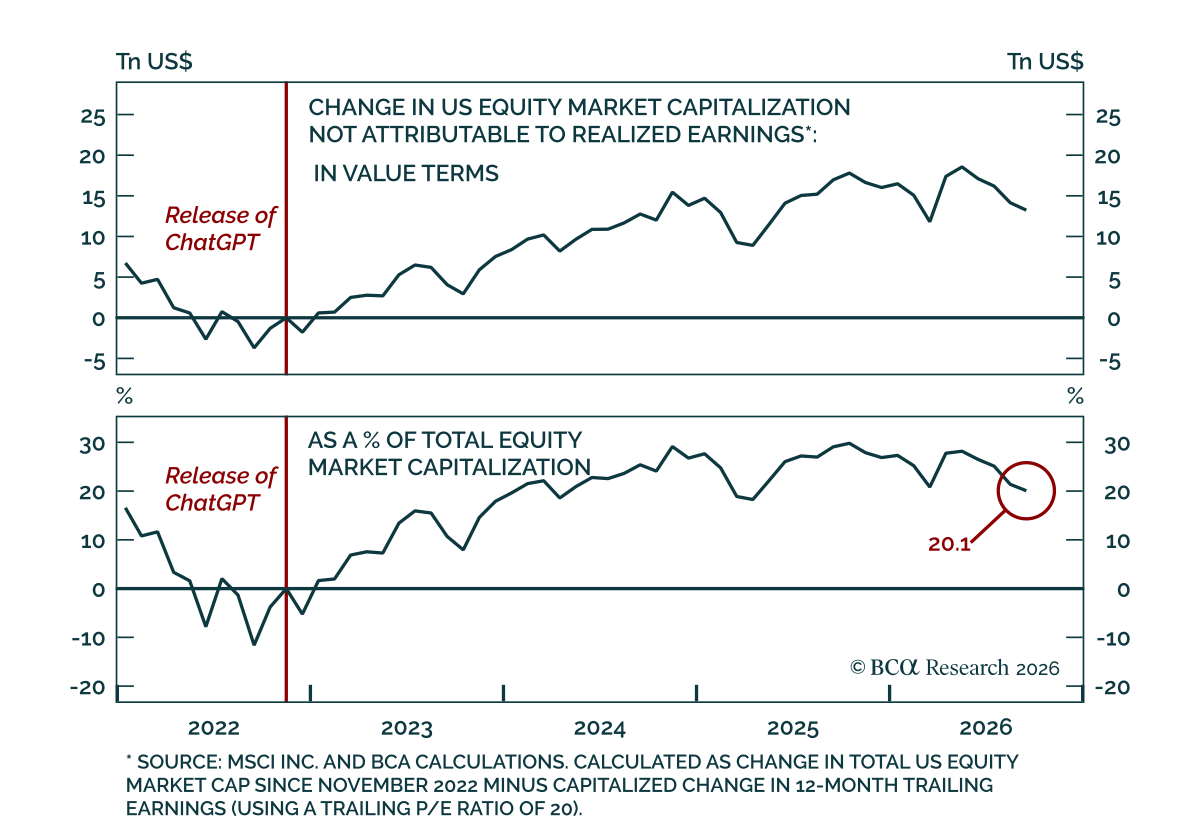
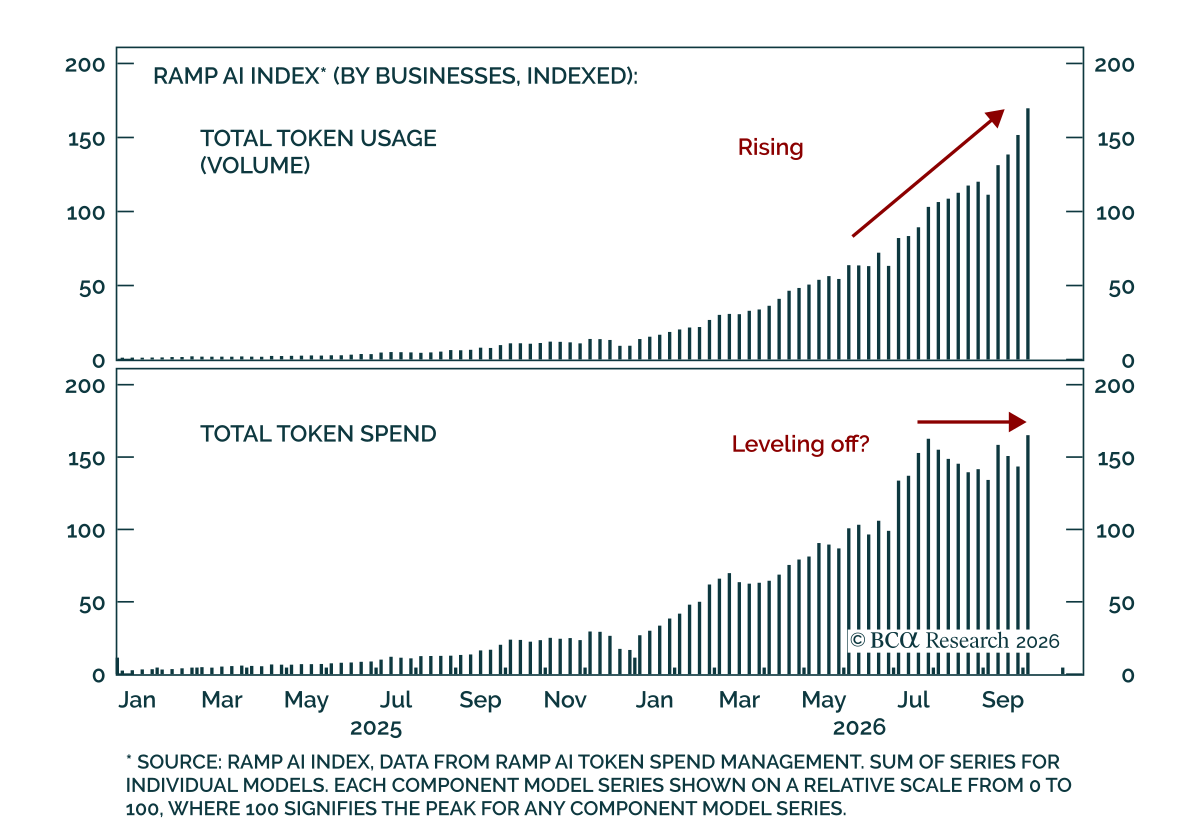
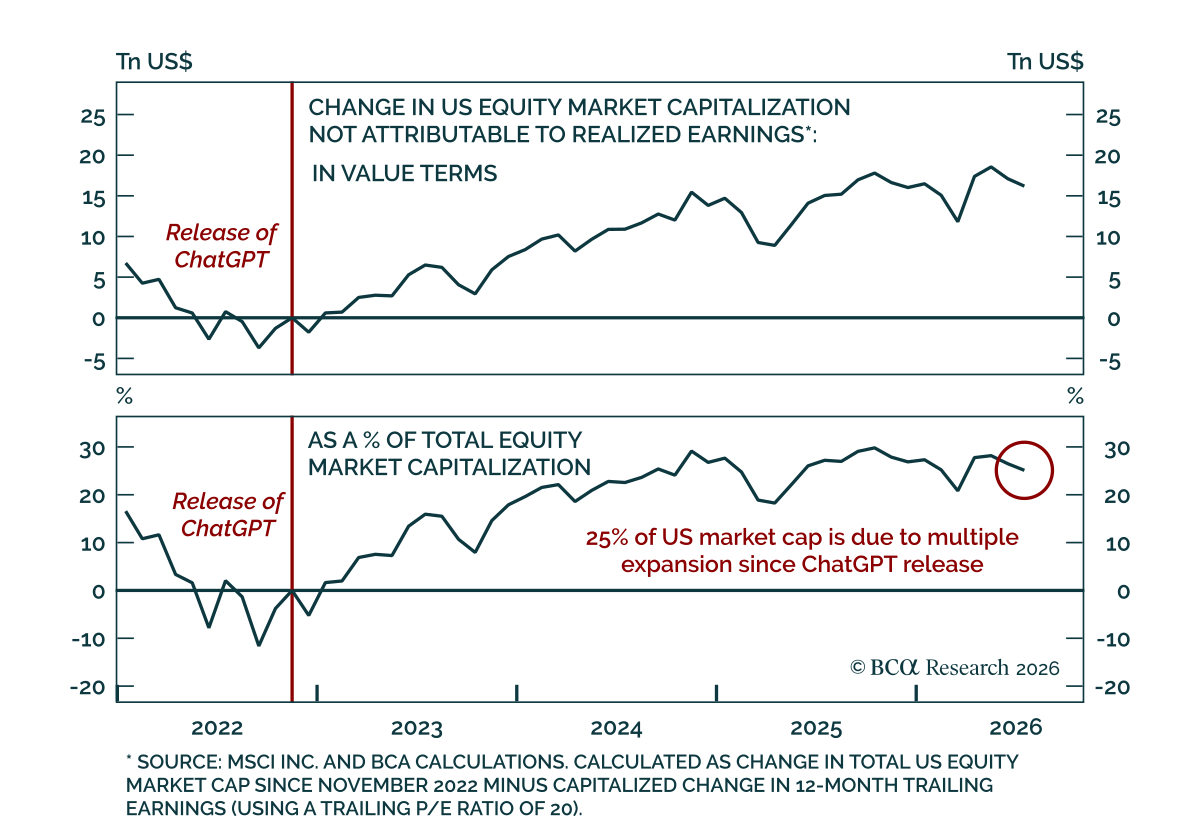

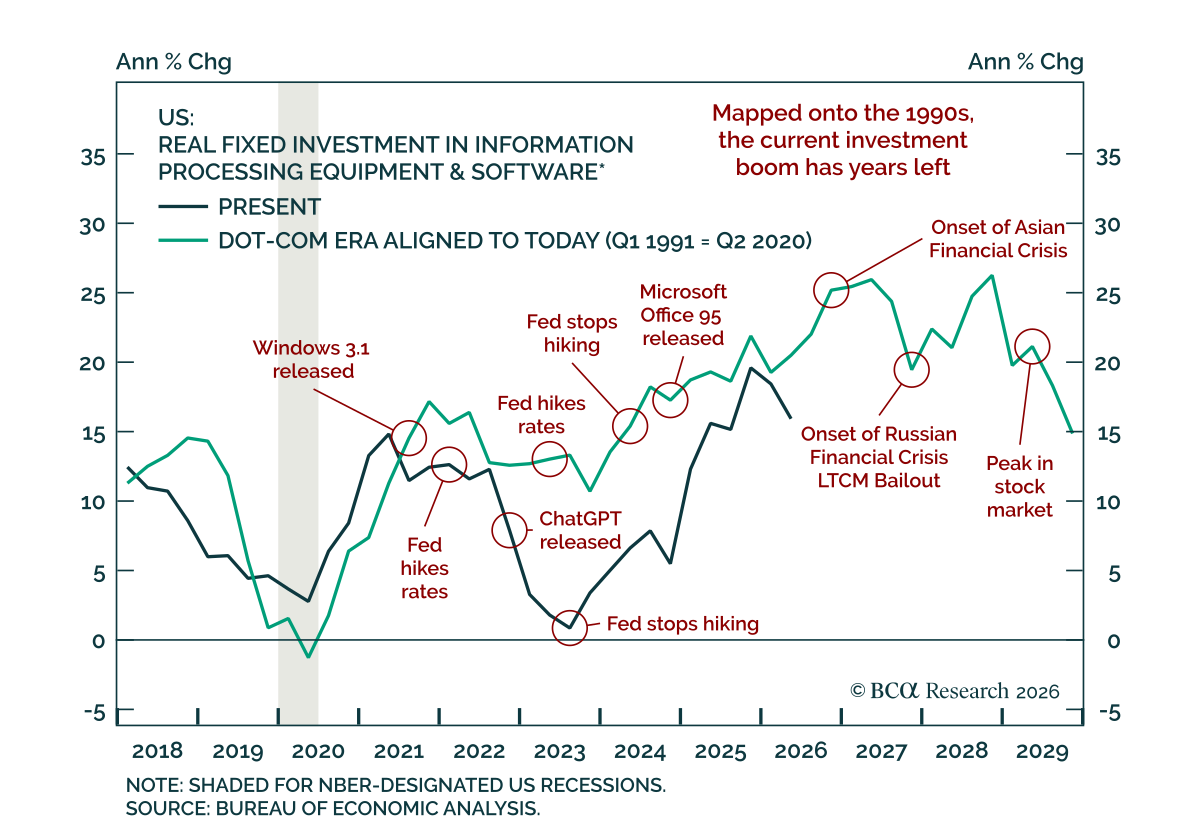
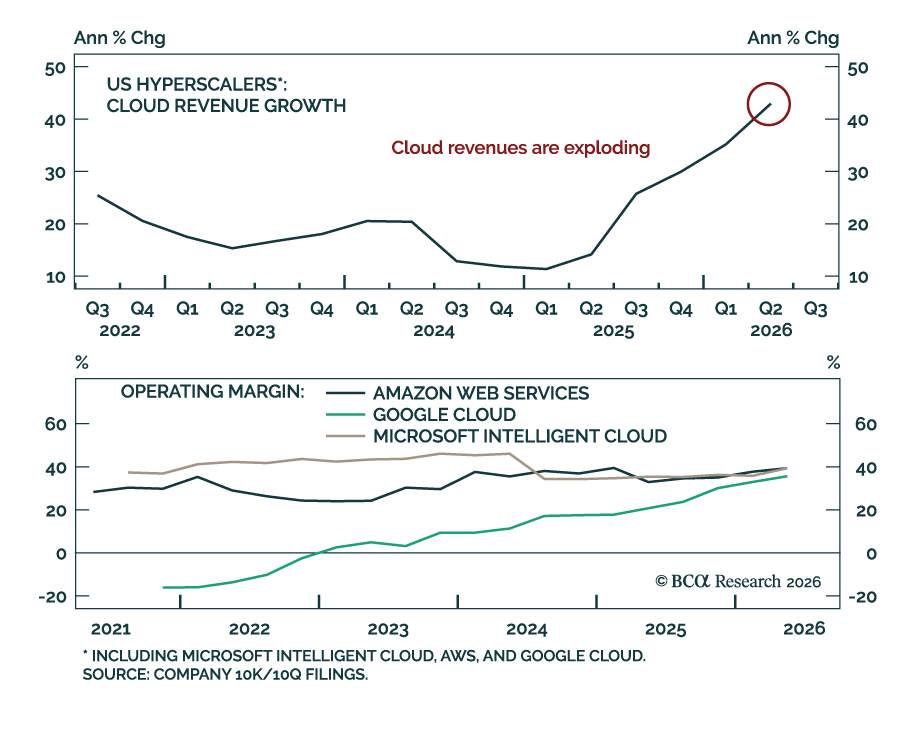
An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury announcement of upsized buyback operations, bond yields are likely to remain elevated over the coming months. Rising crack spreads have reduced the demand for crude, which is not encouraging for global growth. On the FX front, recent intervention to support the yen will probably be insufficient, but there is significant long-term upside for the currency.