Economy

October’s strong labor market report reinforces a December rate hike as the most likely outcome, even as the Fed weighs growth against tighter financial conditions. Nonfarm payrolls rose 165k, well above the consensus estimate of 59k. The unemployment rate…
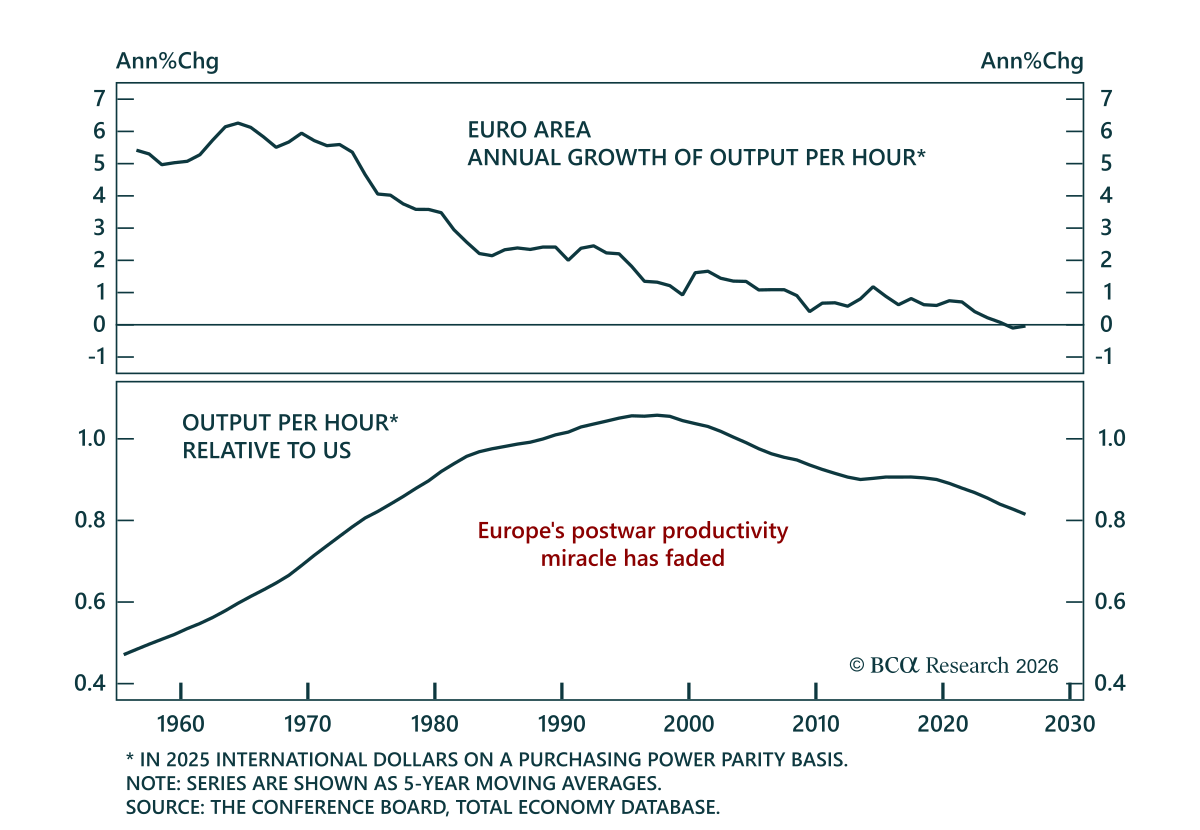
Peter Berezin, our Chief Economist, recommends selling European assets on any rallies. Peter argues repairing Europe’s deep structural problems may require dismantling much of the welfare state, which is unlikely to happen before a major crisis. Lower oil…
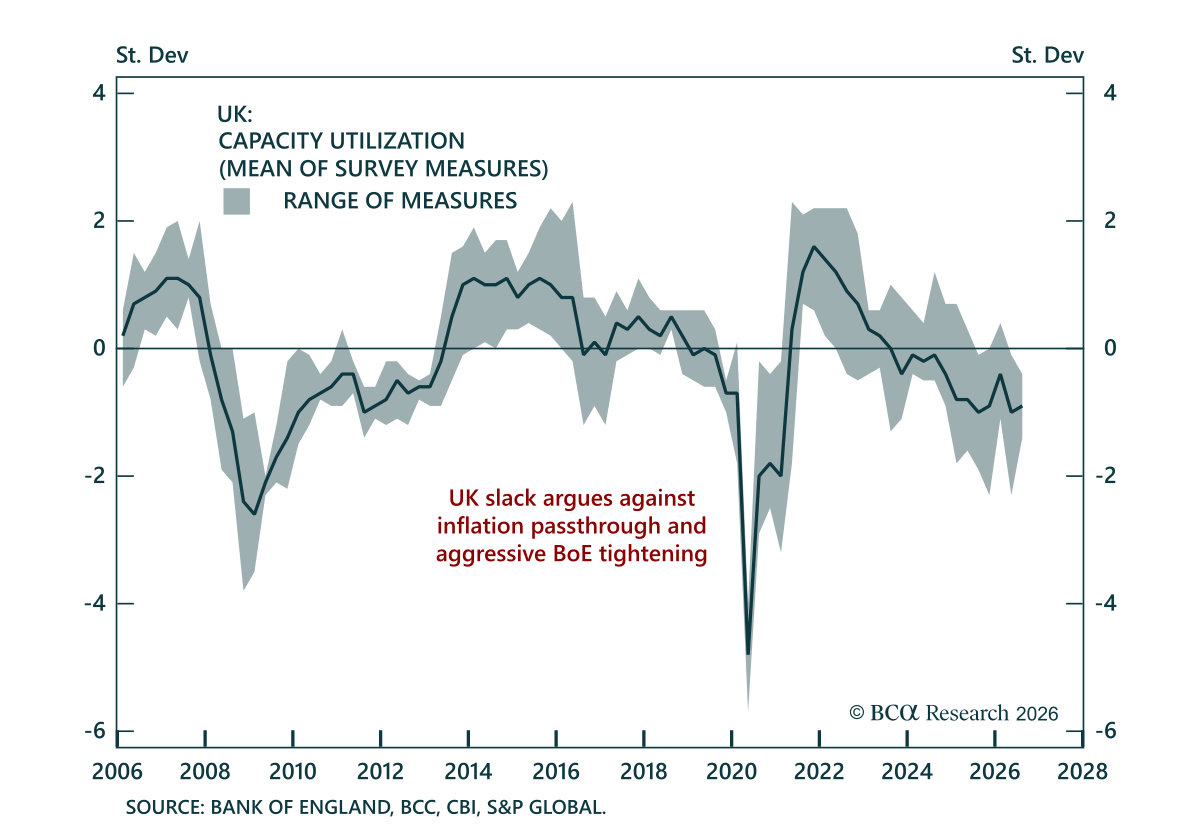
The Bank of England’s 25bps hike to 4% adds to hawkish near terms pricing but creates room for downside surprises in rates later next year. The move was expected, but the unanimous vote to increase rates, with one member favoring a 50bps hike, contrasted with…
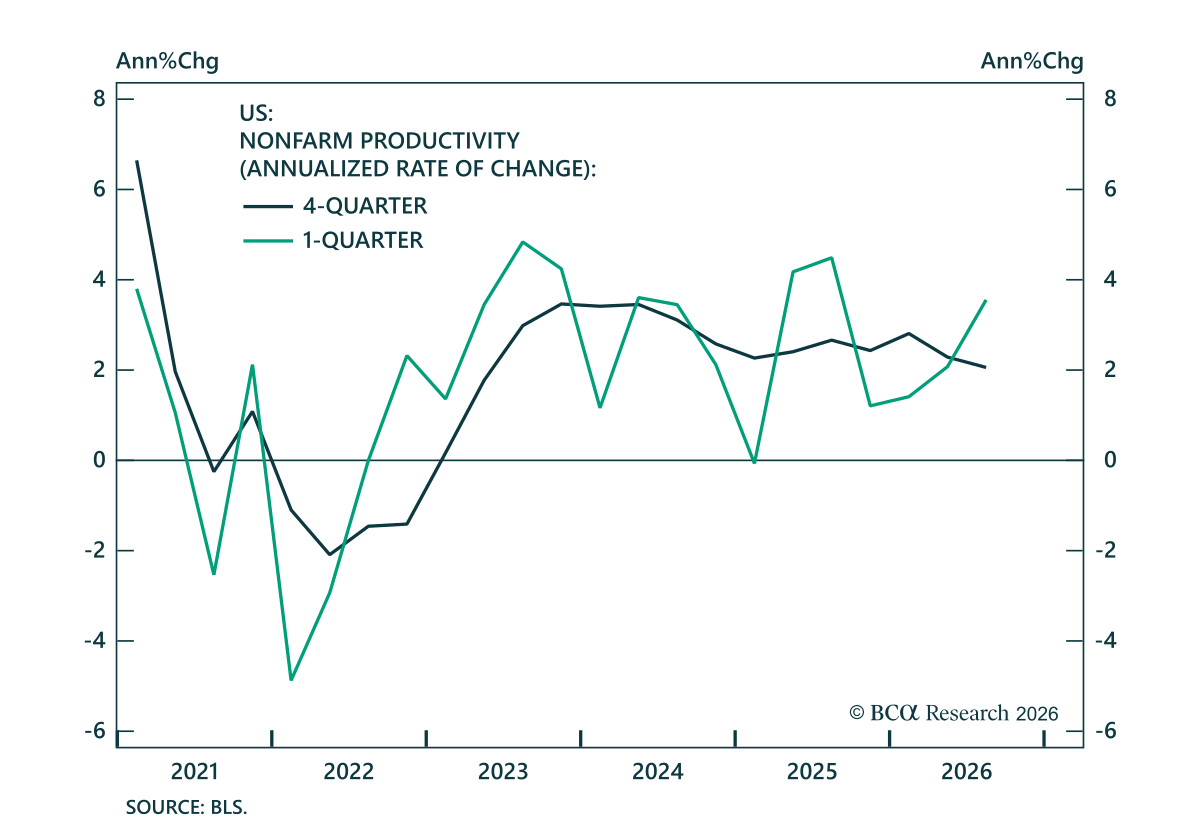
Strong Q3 US productivity reflects the demand-side impact of the AI capex boom, not supply-side gains from ex-tech AI adoption. Preliminary Q3 US nonfarm productivity came in surprisingly strong, growing at a 3.6% annualized q/q rate versus expectations of…
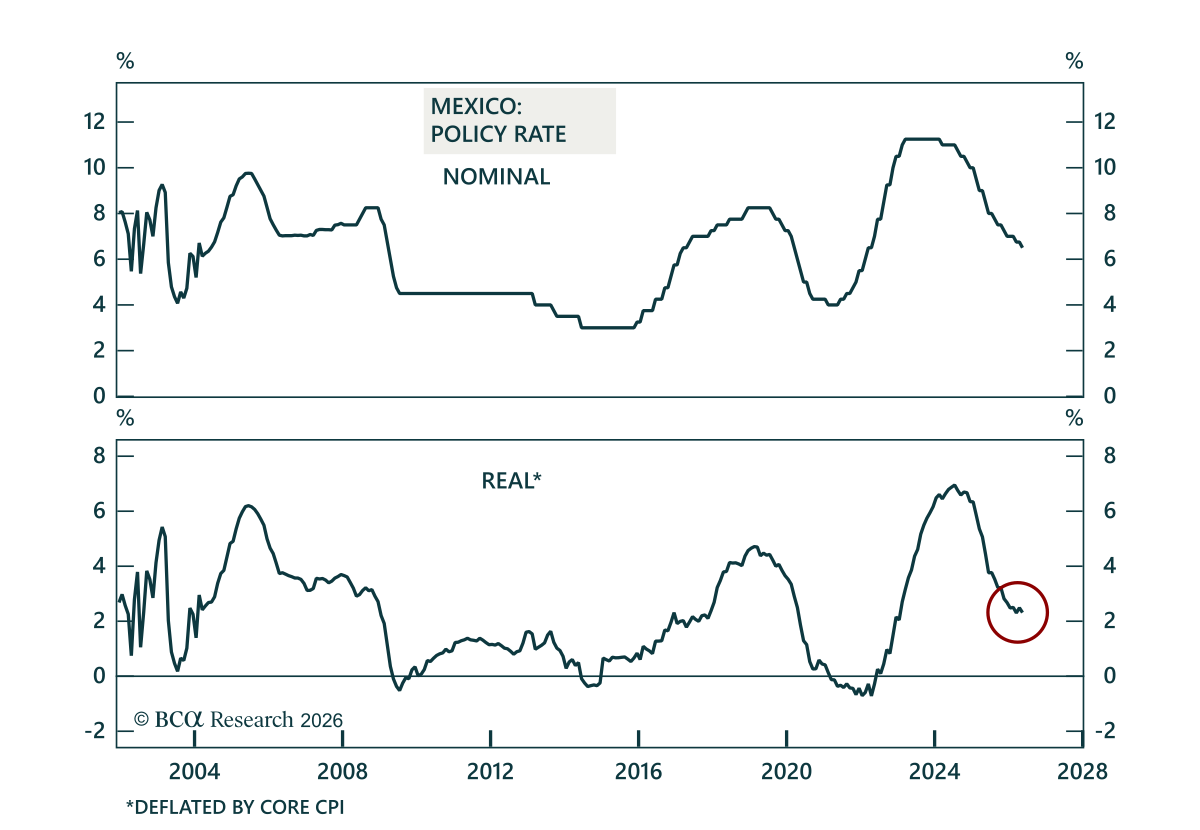
Banxico cut its policy rate by 25 bps to 6.25%, contrary to expectations of a hold. The cited reason is the need for a one-time adjustment to tackle the slack in the economy. Headline inflation has slightly accelerated to 3.62%, and core inflation has…

The September JOLTS report adds to the evidence that labor market demand is improving, posing a growing risk to the downtrend in wage growth. Job openings jumped by 333k to 7.52 million, well above the 7.1 million consensus, lifting the job…
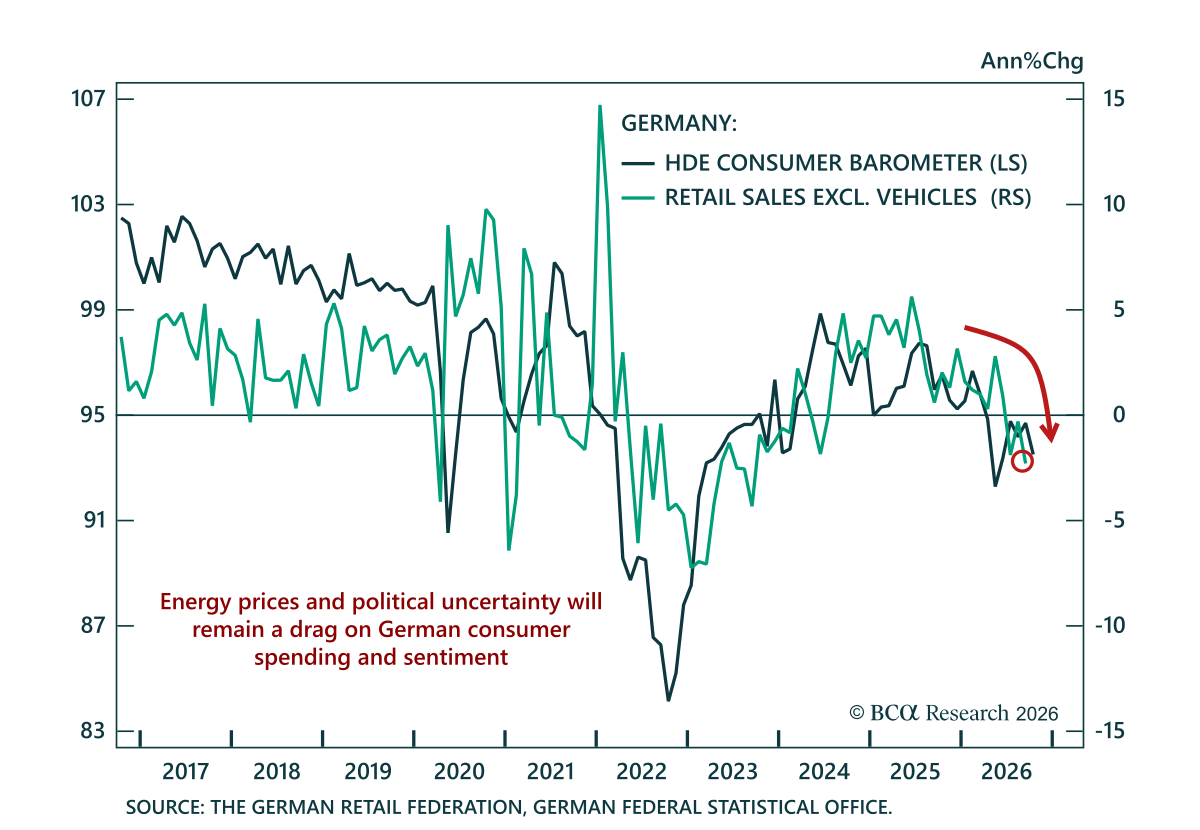
Germany’s September retail sales miss clouds the euro area consumption outlook and supports overweighing German Bunds over US Treasurys. Retail volume ex-vehicles contracted 2% month-on-month, significantly underperforming expectations of 0.4% growth. It was…

US Treasury yields have fallen below our fair value estimate as investors rotated out of AI equities and into fixed income. We lay out why near-term inflation risks argue for a rebound, and the tactical trades we initiate to position for it.

Today's report examines several of the most interesting ideas we've heard over two weeks of meetings and calls with investors.

MacroQuant recommends a slight underweight to equities and an overweight to bonds and cash. The model is bullish on the US dollar, negative on gold, very negative on copper, and neutral on oil.