Skip to main content

Currencies

The October jump in Swiss headline inflation does little to support bets on sustained SNB rate increases and leaves the franc as the most attractive funding currency for carry trades. Inflation accelerated to 1.5% year on year in October, the highest since…

MacroQuant recommends a slight underweight to equities and an overweight to bonds and cash. The model is bullish on the US dollar, negative on gold, very negative on copper, and neutral on oil.
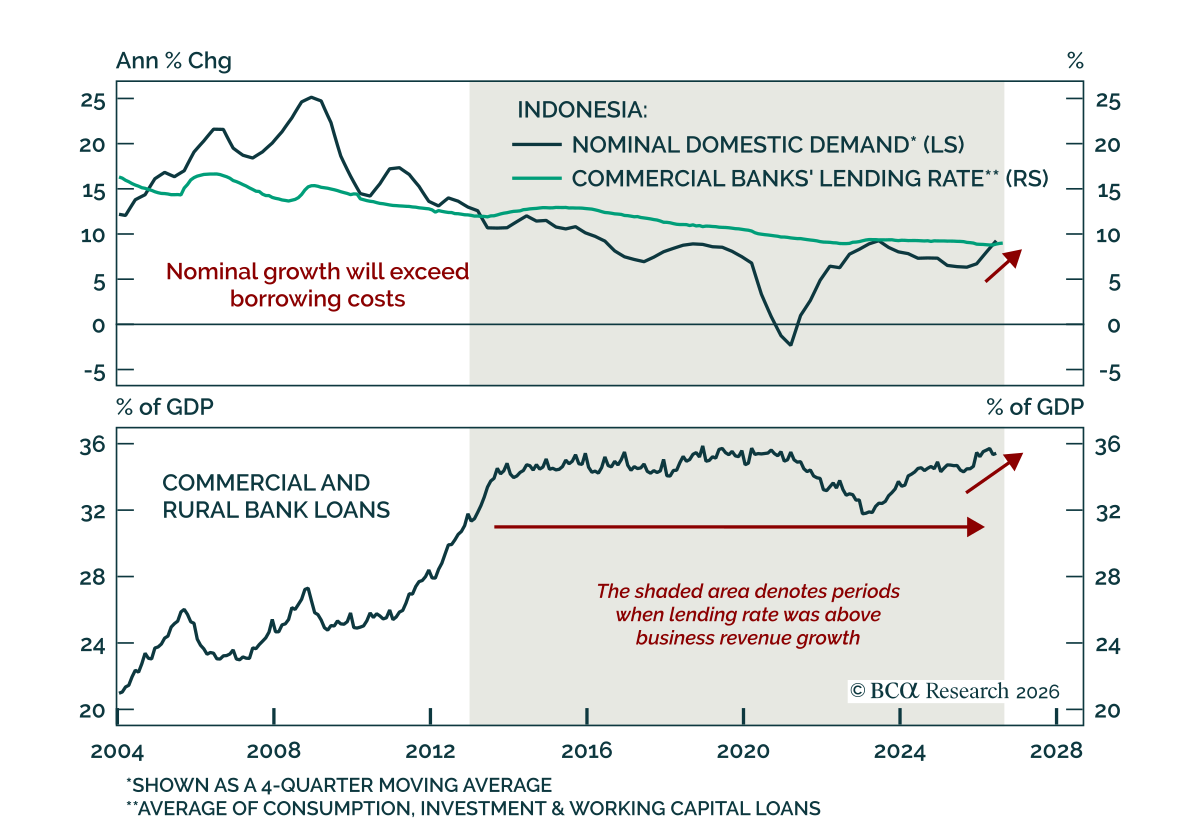
Our EM strategists see Indonesian financial assets as a value trap rather than a buying opportunity. There is room for the ongoing sell-off in Indonesian assets to run further as the country’s macro backdrop deteriorates. President Prabowo’s growth push will…

GBP offers attractive carry today, but the market’s aggressive rate hike pricing is likely to turn into a headwind within 12 months. Our latest Currency Chartpack examines the valuation, growth, rate, and policy drivers of the pound, showing why the long-term outlook is less rosy than near-term data implies.
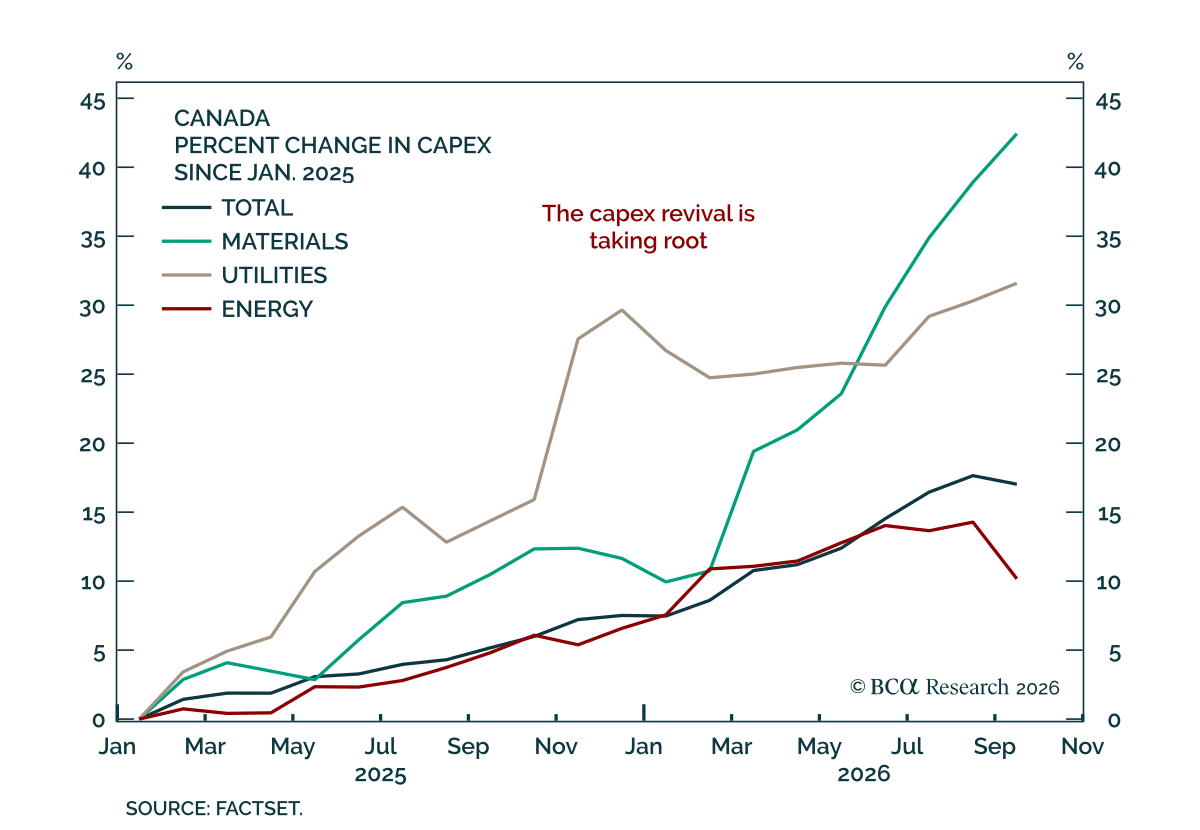
Our FICC strategists believe that CAD and Canadian equities are likely to lag in the near term, but both should outperform over a three-to-four-year horizon. Housing will remain a drag next year and labor market weakness will likely hurt consumption. Wealth…
Special Report

Markets expect the BoC to hike by 100 bps over the next year; we do not. Housing and labor weakness argue for owning Canadian bonds now, while Carney’s reforms and a resource capex wave make the CAD and resource stocks multi-year winners.
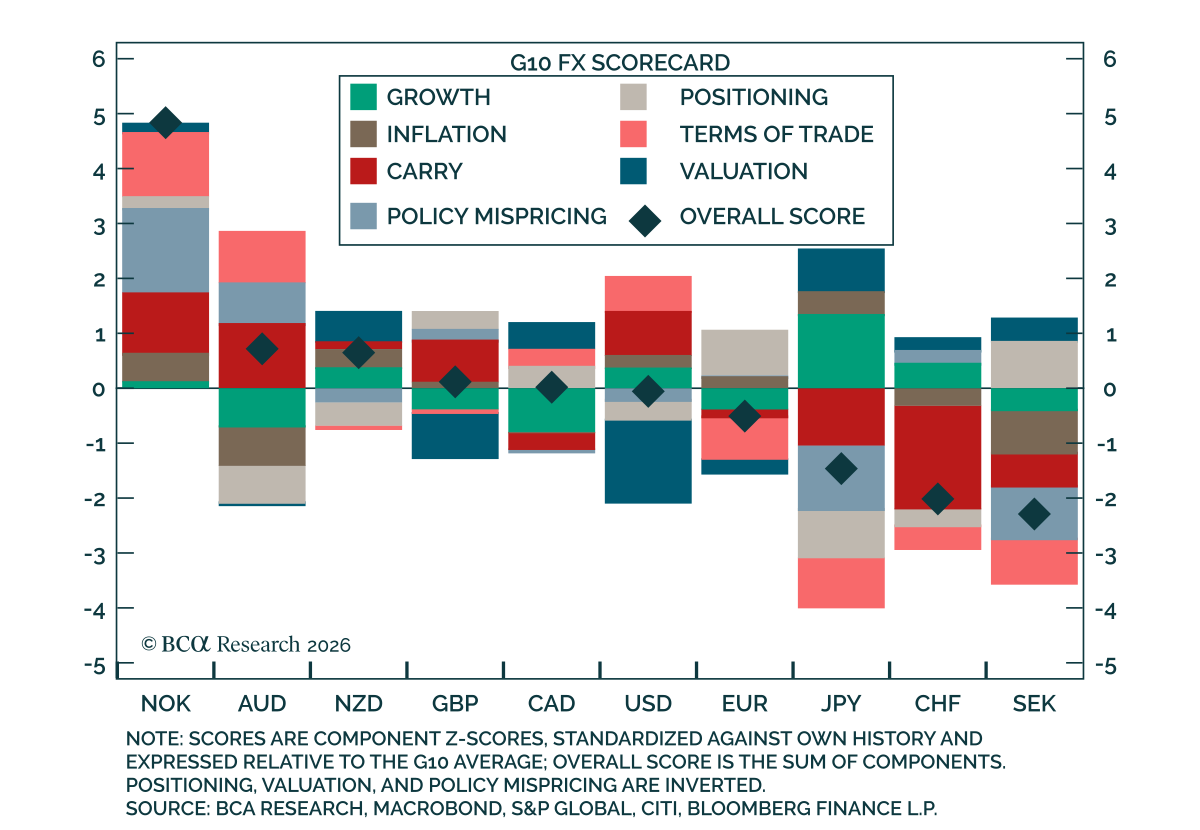
Our FX strategists still recommend long-carry stance with the high-yielders in G10 FX, favoring NOK and AUD against SEK, CHF, and EUR. Several of these positions have run a long way and look stretched, but with low volatility and no imminent catalyst for a…

Our G10 FX cyclical scorecard still favors high-carry currencies over low yielders, suggesting patience should continue to pay. We break down the factors driving each currency and highlight the most appealing relative-value opportunities.

Our FICC strategists recommend staying long risk, holding neutral duration, and fading volatility spikes over the next six to nine months. While worries keep piling up, spanning politics, wars, higher yields, and doubts about AI, our colleagues argue the one…

Politics, wars, a global tightening cycle, doubts over AI capex: the wall of worry keeps rising. But the spark that would topple risk assets is missing. Our Q4 FICC outlook explains why to stay long risk, and where the danger lies.