Geopolitics
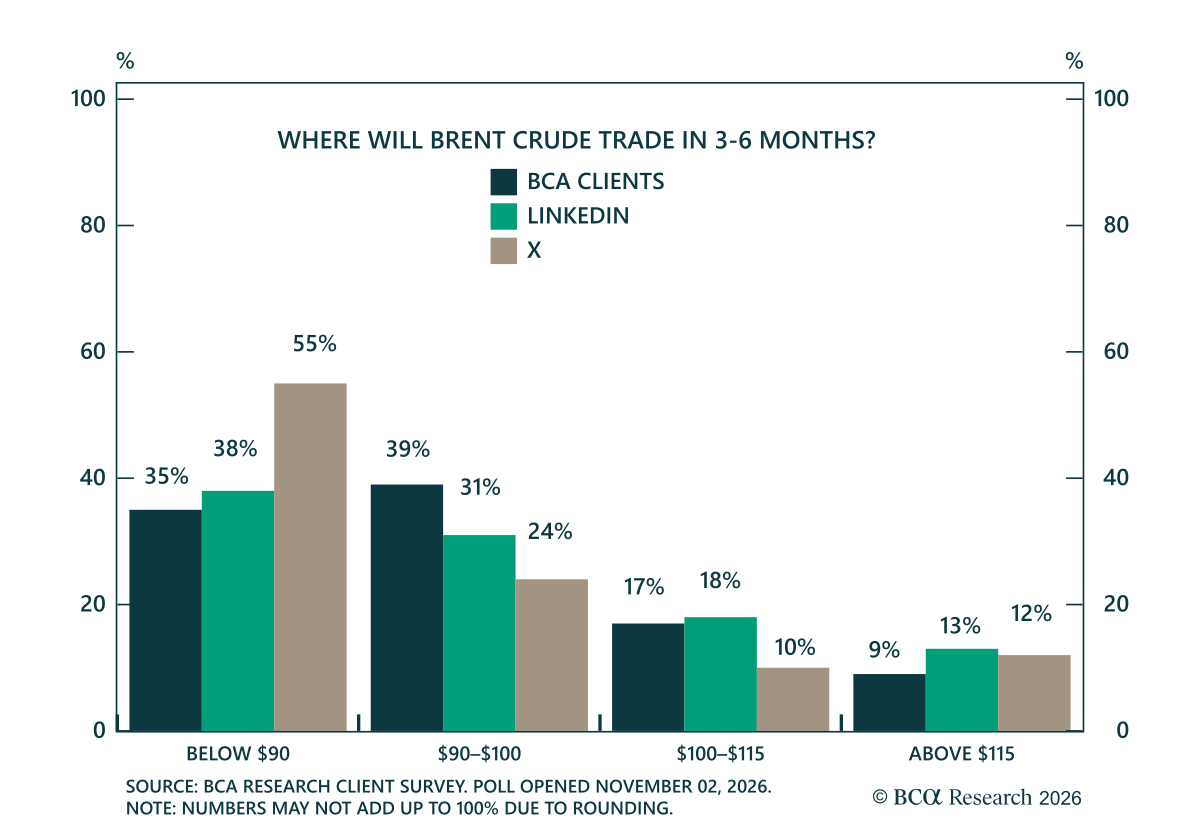
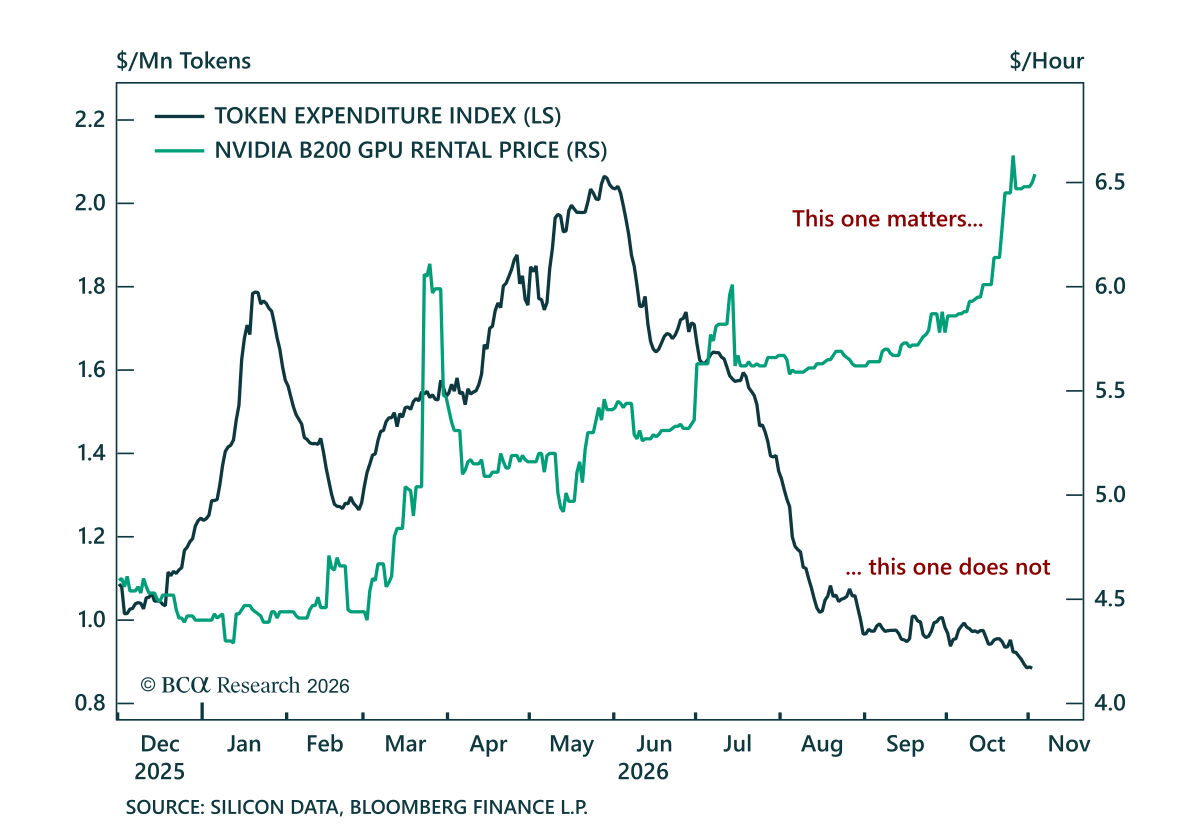

October has been a bad month for equities — particularly AI/tech ones — and a great month for oil. We do not think that the AI supercycle is ending, it has more room to go. Token price decline is a sign of a price war between LLMs, not a decline in demand. In fact, that price war is what is driving datacenter profitability, which is what the bull market is actually based on.
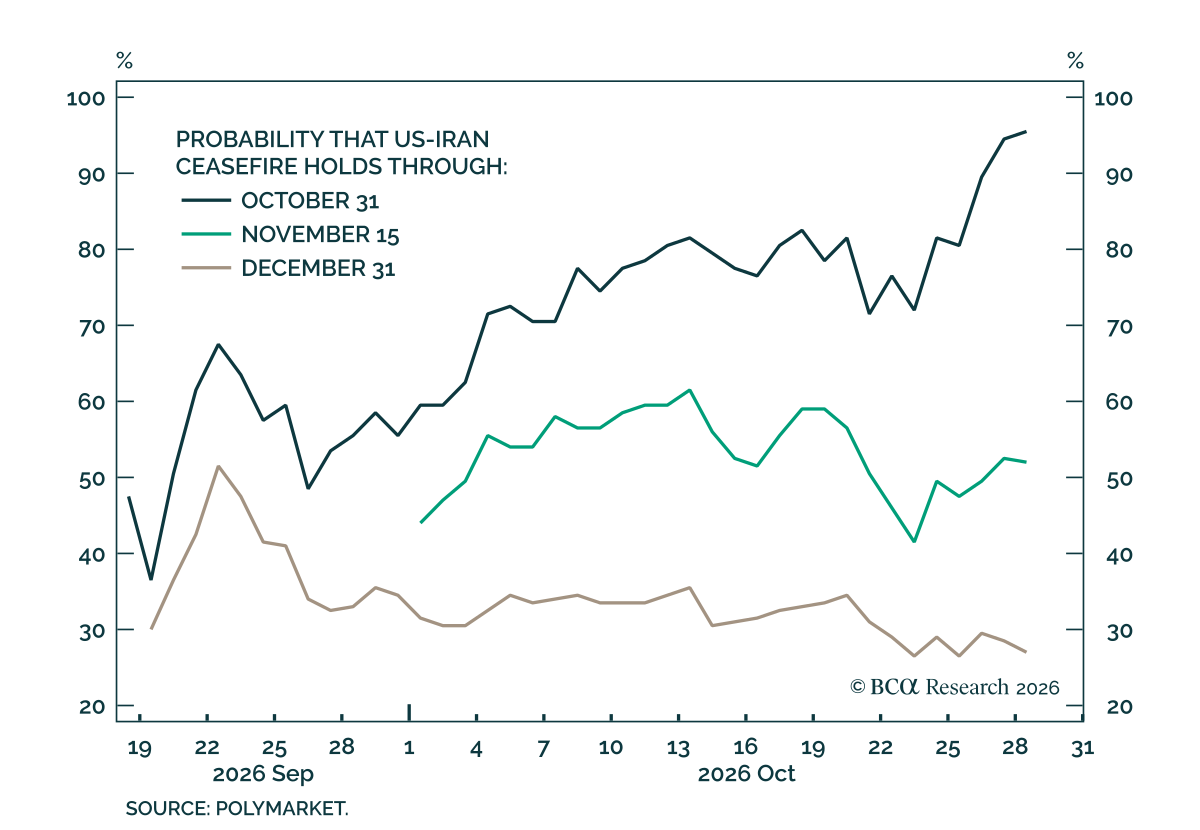
As such, what matters on a tactical time horizon is whether Trump capitulates on Iran. If he does not, the market will have to correct. We take the bullish side and expect oil prices to decline imminently, forcing a short squeeze and powering equities higher.


Europe has 99 problems, but the paucity of bearish views about the Old Continent is not one of them! And yet, somewhat shockingly, European assets have outperformed US assets over the past two years. Sure, markets make mistakes. But the macro graveyards are littered with investors who thought they were smarter than the markets. In this report, we suggest that Europe is on a cusp of significant structural reforms that will unlock value in its services sector. And that while many of the challenges are real, they’re either well understood or priced in.

Iran is effectively trying to create an “October surprise,” an adage that refers to a pre-election crisis that alters the trajectory of polling and the eventual outcome. It is likely to be successful, with oil prices likely to face upward momentum from here. The intention would be to ensure that oil prices do not see any significant decline from now until November 3.

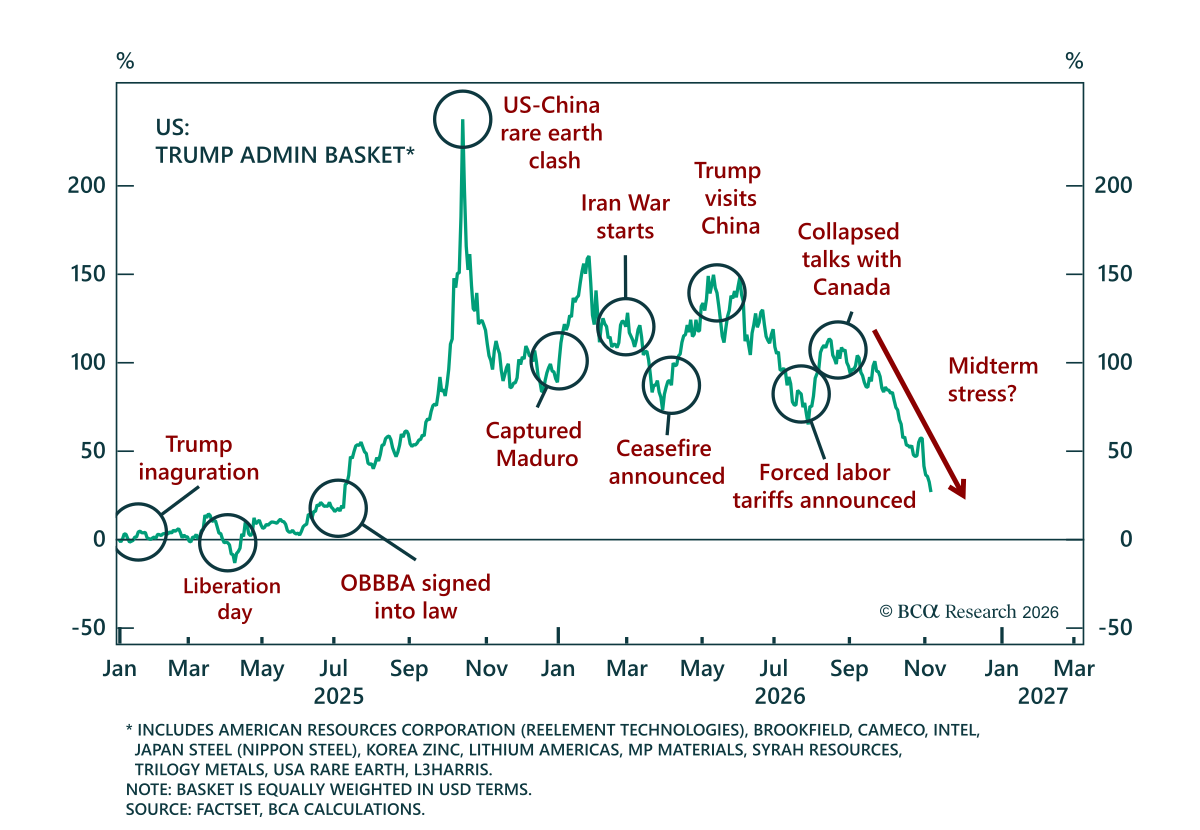
The big risk for the markets remains a flare up in the Middle East conflict. The Fed appears to be targeting geopolitics as much as inflation fundamentals. By the logic of transitive properties, therefore, more war means more hikes. That’s negative. So why are we not bearish on equities and bonds? Because President Trump holds his own faith in his hands. With his unfavourability near all-time highs (Chart of the Month), the conflict in Iran is at its end. Our worry? A Democratic Party sweep that surprises in its intensity and thus forces markets to start pricing in a leftward tilt in 2028.

Middle Eastern crude exports are back at pre-war levels, yet Brent remains above $100/bbl. We explain why more barrels haven’t meant lower prices, and why policymakers have no clean fix. Even if Putin follows through on his reported agreement to release Russian diesel supplies into global markets, it is unlikely to meaningfully ease the fuel's supply disruption over the near term.