Iran
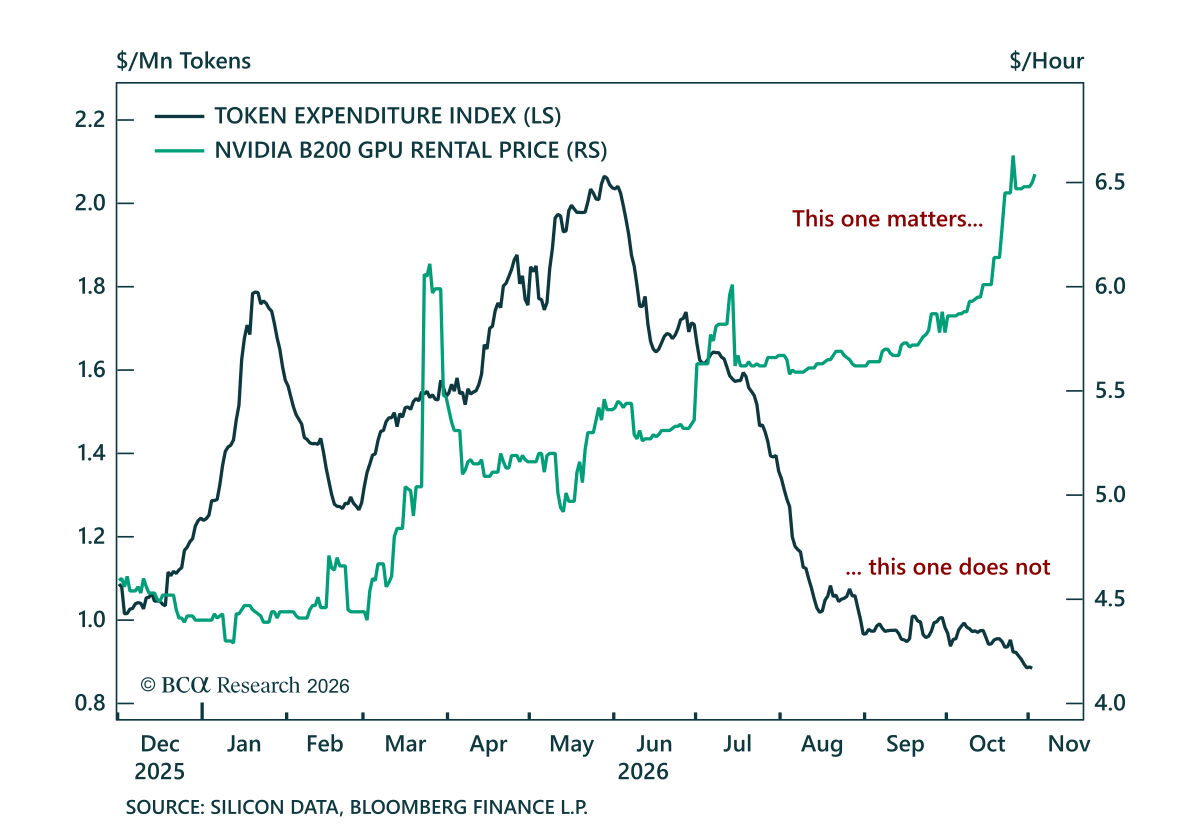

October has been a bad month for equities — particularly AI/tech ones — and a great month for oil. We do not think that the AI supercycle is ending, it has more room to go. Token price decline is a sign of a price war between LLMs, not a decline in demand. In fact, that price war is what is driving datacenter profitability, which is what the bull market is actually based on.
As such, what matters on a tactical time horizon is whether Trump capitulates on Iran. If he does not, the market will have to correct. We take the bullish side and expect oil prices to decline imminently, forcing a short squeeze and powering equities higher.
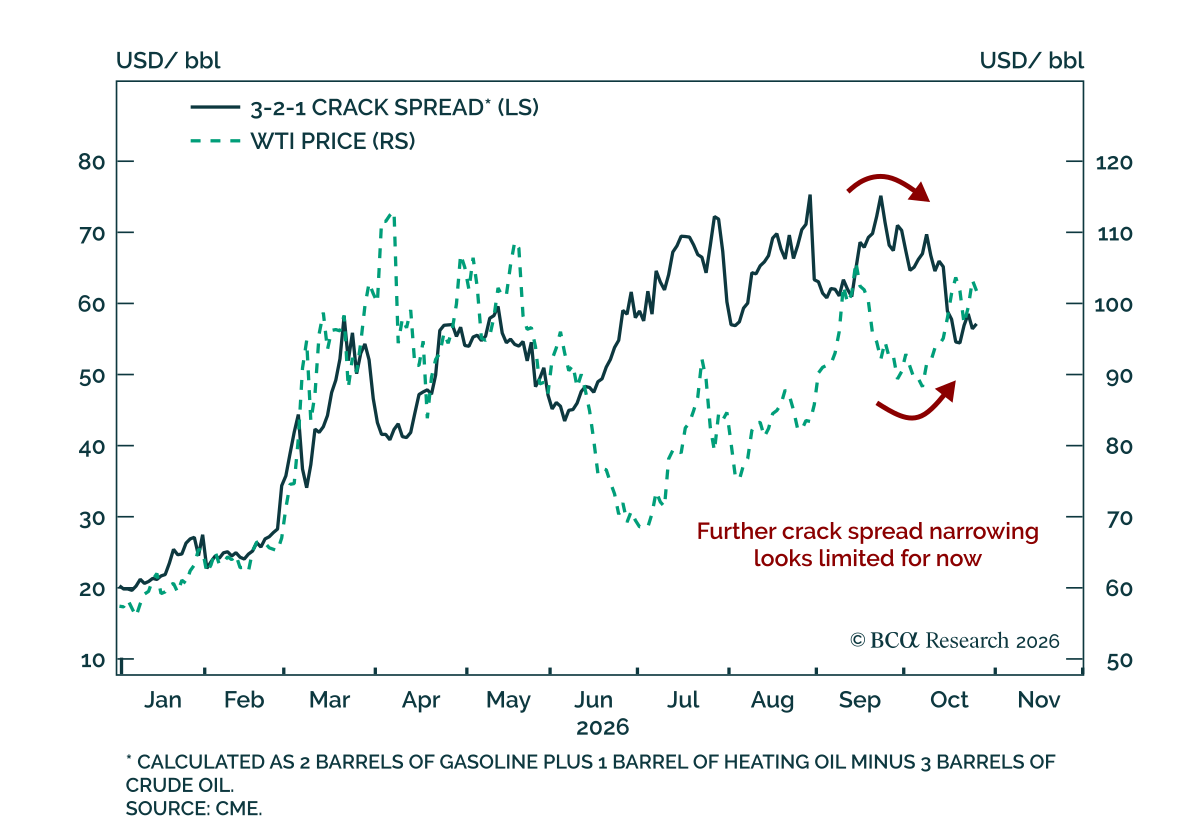

Crude has led the latest rally, leaving refined product prices behind and crack spreads narrower. We explain why the spread compression is unlikely to continue and why product prices will follow crude.


Iran is effectively trying to create an “October surprise,” an adage that refers to a pre-election crisis that alters the trajectory of polling and the eventual outcome. It is likely to be successful, with oil prices likely to face upward momentum from here. The intention would be to ensure that oil prices do not see any significant decline from now until November 3.
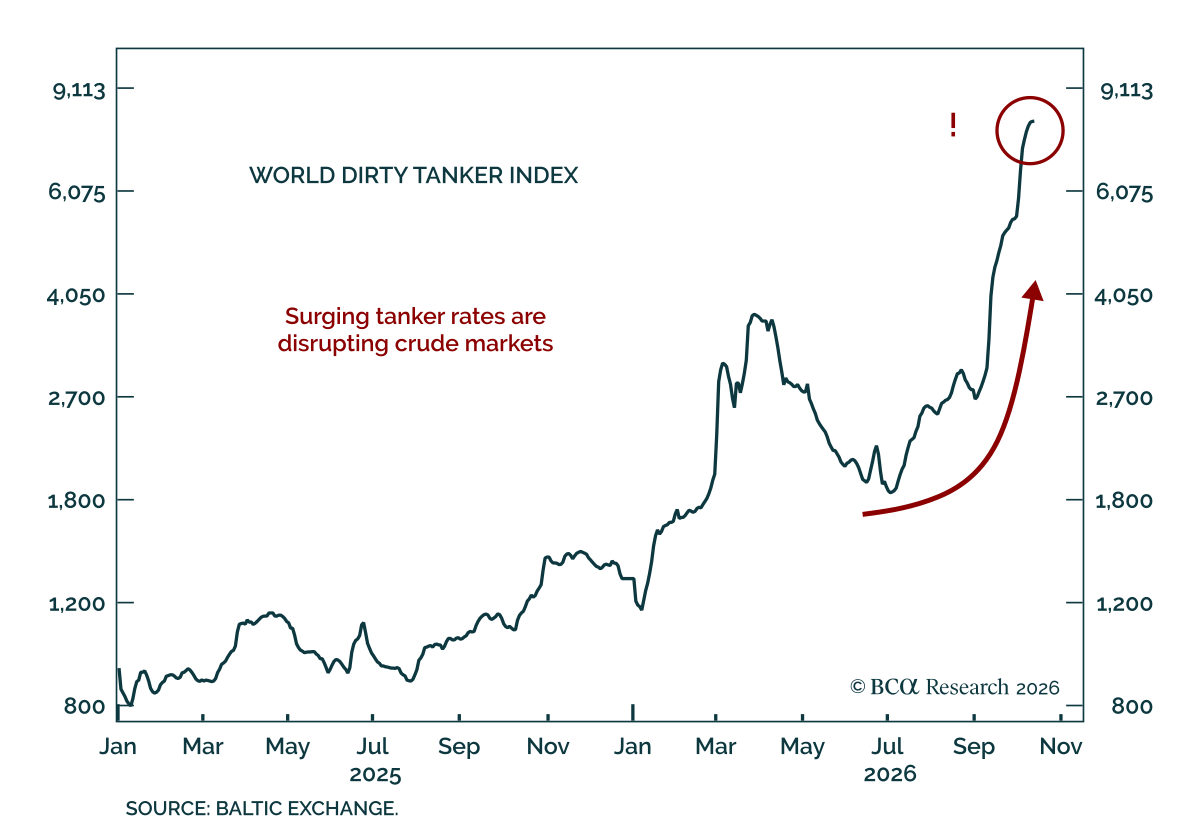

Middle Eastern crude exports are back at pre-war levels, yet Brent remains above $100/bbl. We explain why more barrels haven’t meant lower prices, and why policymakers have no clean fix. Even if Putin follows through on his reported agreement to release Russian diesel supplies into global markets, it is unlikely to meaningfully ease the fuel's supply disruption over the near term.
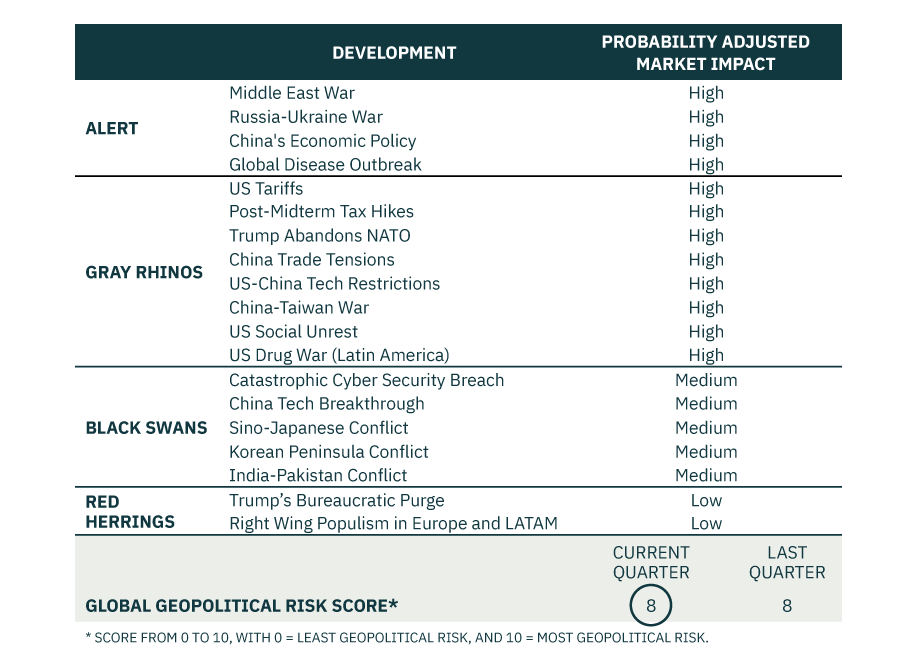

We keep the Global Geopolitical Risk Score at 8 because there are still no ceasefires in Europe or the Middle East. Russia is provoking NATO, which will need to push back. Iran, emboldened by the lack of definitive US success, pushes its luck, which could invite a destructive response from the US. The Chinese economy remains fragile, increasing the likelihood of foreign belligerence. After the US midterm, President Trump faces fewer political constraints, allowing him to pursue a maximalist foreign policy to cement his legacy during his lame-duck period.